Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

How to Choose a Medigap Policy 2027: A Step-by-Step Guide

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 15, 2026

Every year Medicare publishes a booklet called Choosing a Medigap Policy. It’s thorough, but it’s long. This guide covers the same decisions in plain language, in the order you’ll actually make them.

Here’s how to choose a Medigap policy for 2027, step by step, plus the mistakes that cost people money.
Compare 2027 Medigap Policies in Your Area

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

The Four Things That Matter Most

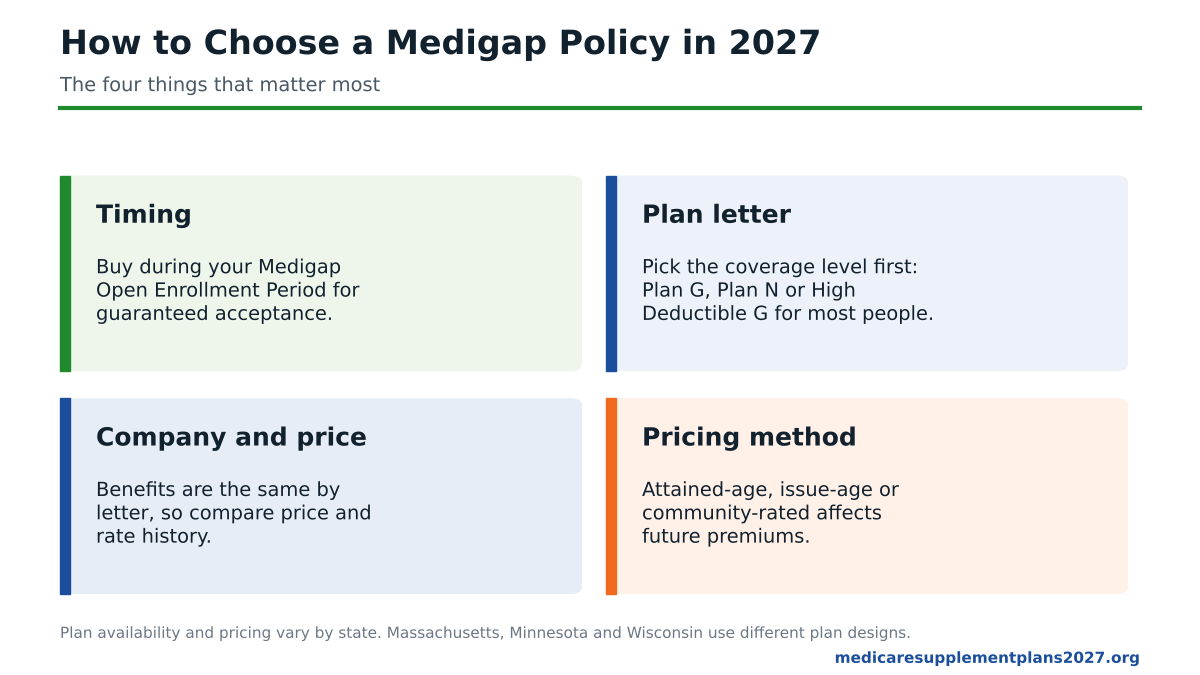
How to choose a Medigap policy in 2027: timing, plan letter, company and price, and pricing method

Choosing a Medigap policy comes down to four decisions: when you buy, which plan letter you pick, which company you buy from, and how the policy is priced over time. Get those four right and you’ve done 90% of the work.

Step 1: Know Your Timing

Best time to buy: your Medigap Open Enrollment Period, the 6 months starting when you’re 65 or older and enrolled in Part B. During that window, carriers must accept you and can’t charge more because of your health.

Miss that window and most carriers can ask health questions, charge more or decline you. Read the full rules in Medigap Open Enrollment Period 2027.

Step 2: Choose Your Plan Letter

Plan Best for
Plan G The most complete coverage for people new to Medicare. You pay only the Part B deductible.
Plan N A lower premium in exchange for small copays at some visits.
High Deductible Plan G The lowest premium, with a $3,050 deductible in 2027 before coverage kicks in.
Plan F Only for people eligible for Medicare before 2020.

See all 10 plans side by side in the Medicare Supplement plans comparison chart 2027, or compare the two most popular in Plan G vs Plan N 2027.

Step 3: Compare Companies for the Same Letter

Medigap benefits are standardized by federal law, so a Plan G from one company pays exactly the same as a Plan G from another. Once you’ve picked your letter, you’re shopping on:

  • Price. The same plan can cost very different amounts in the same ZIP code.
  • Rate increase history. A low first-year price means little if the carrier raises rates sharply every year.
  • Financial strength. Look for solid A.M. Best ratings.
  • Discounts. Household discounts can save around 10% with many carriers.

Top carriers to compare include Mutual of Omaha, HealthSpring, Wellabe and ACE by Chubb.

Compare Medigap Policies in Your ZIP Code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Step 4: Understand How the Policy Is Priced

  • Attained-age: starts lower and rises as you get older. This is the most common method.
  • Issue-age: based on your age when you buy. It doesn’t rise because of age.
  • Community-rated: everyone pays the same regardless of age.

All three can still increase over time for other reasons. Compare the long-term cost, not just the first year. See typical prices in Medicare Supplement Plans Cost 2027.

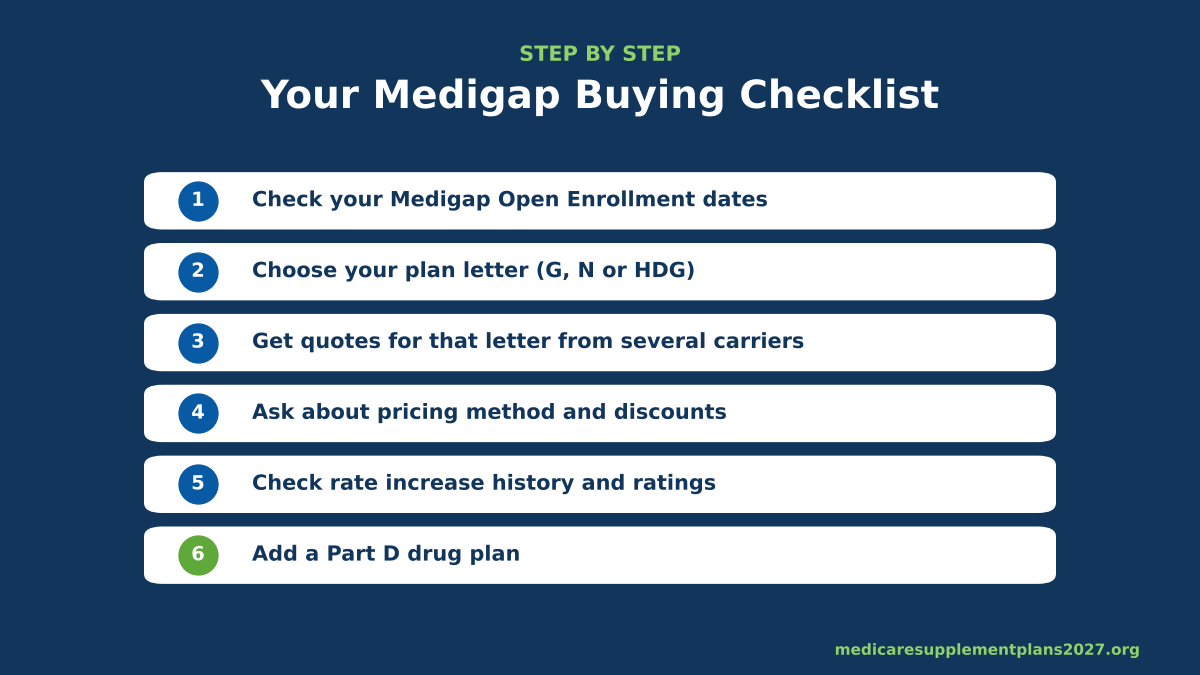
Your Medigap Buying Checklist

Six-step Medigap buying checklist for 2027, from open enrollment dates to adding a Part D plan

Mistakes to avoid:

  • Missing your Medigap Open Enrollment Period
  • Choosing by brand name instead of comparing price for the same letter
  • Ignoring a carrier’s rate increase history
  • Forgetting to add a Part D drug plan
  • Canceling existing coverage before the new policy is approved

Compare 2027 Medicare Supplement Rates & Benefits

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

How to Choose a Medigap Policy FAQs

➤ What is the first step in choosing a Medigap policy?

Start with timing. Your Medigap Open Enrollment Period, the 6 months starting when you’re 65 or older and enrolled in Part B, is when carriers must accept you at standard rates regardless of health.

➤ Which Medigap plan should I choose?

Most people new to Medicare choose Plan G for the most complete coverage available to them, Plan N for a lower premium with small copays, or High Deductible Plan G for the lowest premium with a $3,050 deductible in 2027.

➤ Does it matter which company I buy my Medigap policy from?

Benefits are the same for each plan letter no matter the company, but price, discounts, pricing method and rate increase history can differ a lot. That’s what you’re really comparing between carriers.

➤ What pricing method is best for a Medigap policy?

Attained-age plans start lower but rise as you age. Issue-age plans are based on your age when you buy and don’t rise because of age. Community-rated plans charge everyone the same. All three can still go up for other reasons, so compare long-term cost, not just the first-year premium.

➤ What is Choosing a Medigap Policy?

Choosing a Medigap Policy is the official guide published by Medicare and CMS each year. It explains the plan letters, your rights and how Medigap works. This page walks through the same decisions in plain language for 2027.

➤ Do I need a Part D plan with Medigap?

Most people do. Medigap plans sold today don’t cover prescription drugs, so you’ll usually want a stand-alone Part D plan alongside your Medicare Supplement.

➤ Can I change my Medigap policy later?

You can apply any time, but outside your Medigap Open Enrollment Period or a guaranteed issue right, most carriers can ask health questions. Some states have birthday or anniversary rules that make switching easier.

➤ What mistakes should I avoid when choosing a Medigap policy?

Common mistakes include missing your open enrollment window, choosing by brand name instead of price, ignoring rate increase history, and canceling existing coverage before a new policy is approved.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Have Questions?

Speak with a licensed insurance agent

1-855-409-6195

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT