Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Plan G vs Plan N 2027: Which Medicare Supplement Plan Is Better?

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 13, 2026

Plan G and Plan N are the two most popular Medicare Supplement plans for people new to Medicare, and they’re closer than most people think. They cover almost everything the same way. The difference comes down to three things and one price gap.

Here’s how Medicare Supplement Plan G and Medicare Supplement Plan N compare for 2027, and how to tell which one saves you more.
Compare Plan G and Plan N Rates for 2027

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

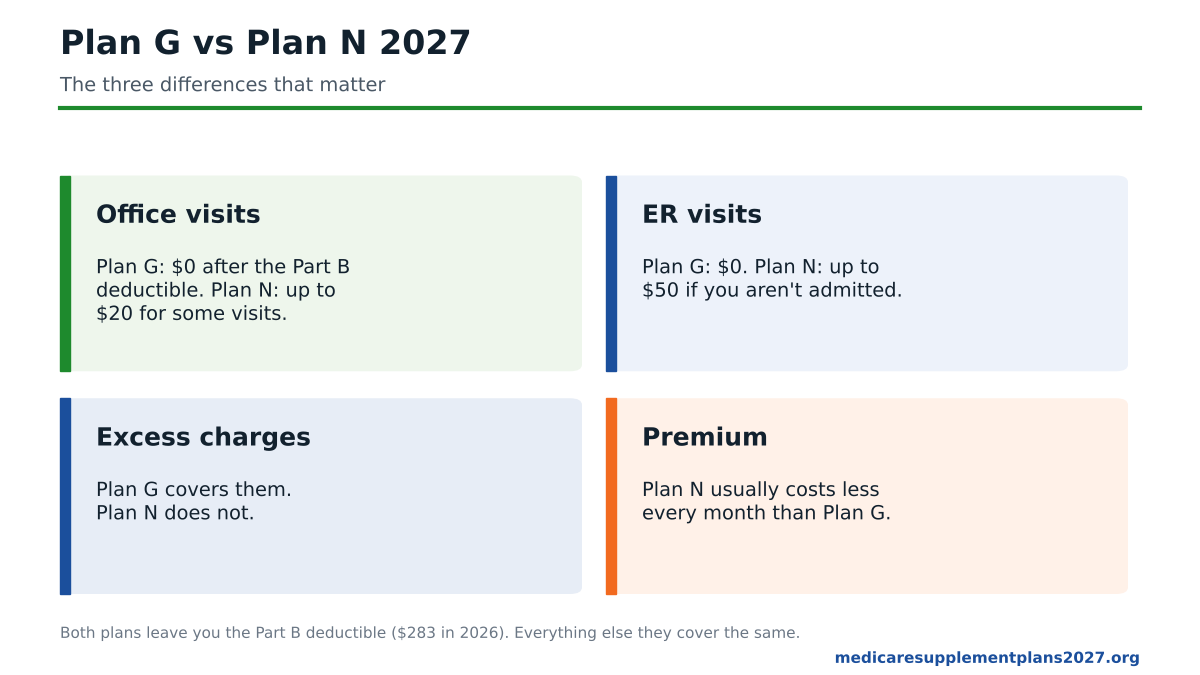
Plan G vs Plan N 2027 coverage differences: office copays, ER copays, excess charges and premium

Plan G vs Plan N: Side-by-Side for 2027

Benefit Plan G Plan N
Part B deductible You pay ($283 in 2026) You pay ($283 in 2026)
Part A deductible Covered Covered
Office visits $0 after the deductible Up to $20 for some visits
ER visits $0 after the deductible Up to $50 if not admitted
Part B excess charges Covered Not covered
Hospital, skilled nursing, hospice Covered Covered
Foreign travel emergency 80% up to plan limits 80% up to plan limits
Monthly premium Higher Usually lower

To see how both stack up against all 10 Medigap letters, use our Medicare Supplement plans comparison chart for 2027.

The Three Differences That Matter

1. Office visit copays. With Plan N you may pay up to $20 for some office visits. With Plan G you pay nothing once the Part B deductible is met.

2. ER copays. With Plan N you may pay up to $50 for an ER visit that doesn’t result in admission. If you’re admitted, the copay is waived.

3. Part B excess charges. Doctors who don’t accept Medicare assignment can charge up to 15% more than the Medicare-approved amount. Plan G covers that. Plan N doesn’t, though most doctors accept assignment and some states ban excess charges outright.

Everything else, including the Part A deductible, hospital stays, skilled nursing and hospice, is covered the same way by both plans.

Compare Plan G and Plan N Rates for 2027

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

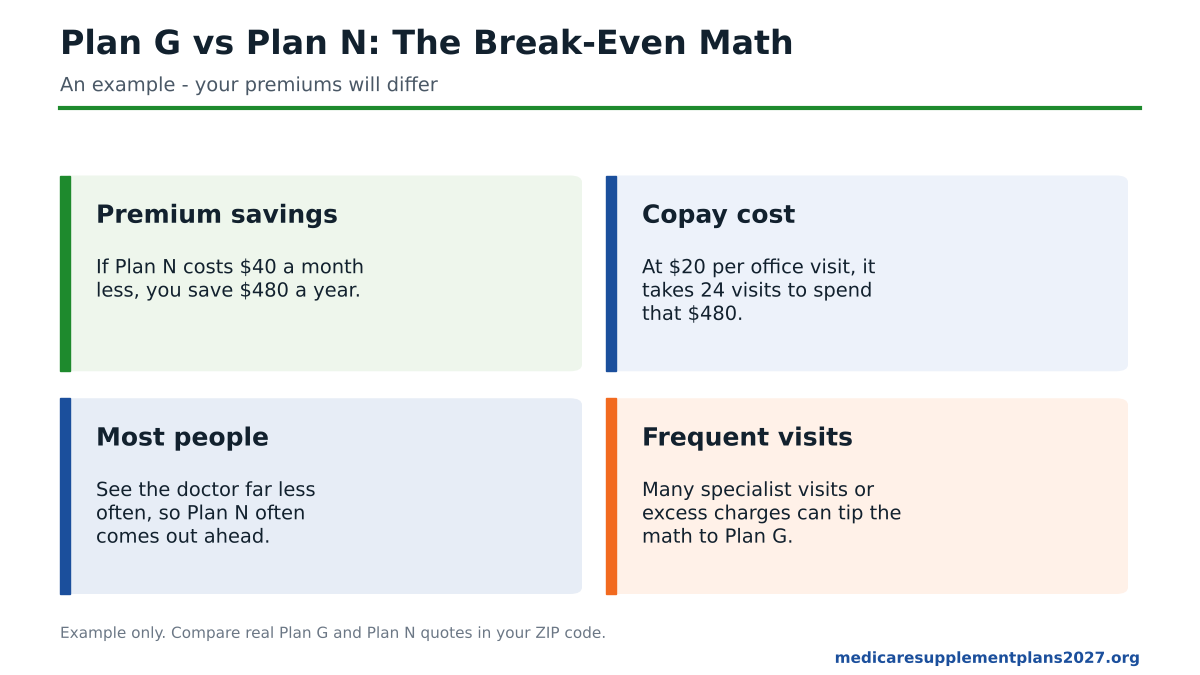
Plan G vs Plan N 2027 break-even math comparing premium savings with Plan N copays

Plan G vs Plan N: The Break-Even Math

The right choice comes down to whether Plan N’s premium savings outweigh its copays. Here’s a simple example. Your real premiums will differ:

  • Premium savings: if Plan N costs $40 a month less than Plan G, you save $480 a year.
  • Copay cost: at $20 per office visit, it takes 24 visits in a year to spend that $480.
  • The result: most people see the doctor far less often, so Plan N often comes out ahead.

The math tips toward Plan G if you see specialists often, visit the ER more than once or twice a year, or use doctors who charge excess charges. For context on Plan G pricing, see our breakdown of Medicare Supplement Plan G cost in 2027.

Who Each Plan Fits

Plan G fits you if you:

  • See doctors or specialists often
  • Want no copays and fully predictable costs
  • Use doctors who don’t accept Medicare assignment

Plan N fits you if you:

  • Are healthy and see the doctor a few times a year
  • Want a lower monthly premium
  • Are fine with small copays in exchange for savings

If neither fits, High Deductible Plan G has the lowest premium of the three. See all our picks for the best Medicare Supplement plans for 2027.

Before You Choose: 2027 Checklist

  1. Get quotes for both plans. The premium gap decides the math.
  2. Count last year’s doctor visits. That tells you what Plan N’s copays would cost.
  3. Ask your doctors about Medicare assignment. If they all accept it, excess charges won’t apply.
  4. Think long term. Switching plans later can require health questions.
  5. Check your timing. Your Medigap Open Enrollment Period gives you guaranteed acceptance.
  6. Add a Part D plan. Compare all Medicare Supplement plans for 2027 alongside your drug coverage.

Plan G vs Plan N for 2027: Compare Rates & Benefits

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Plan G vs Plan N 2027 — Frequently Asked Questions

➤ What is the difference between Plan G and Plan N?

Plan N adds copays of up to $20 for some office visits and up to $50 for ER visits that don’t result in admission, and it doesn’t cover Part B excess charges. Plan G covers all three. In exchange, Plan N usually has a lower monthly premium.

➤ Is Plan G or Plan N better for 2027?

Plan N is often the better value for healthy people who see the doctor a few times a year. Plan G is better if you see specialists often, want no copays at all, or live where doctors commonly charge excess charges.

➤ Do Plan G and Plan N have the same deductible?

Yes. Both leave you to pay the Medicare Part B deductible, which was $283 in 2026. CMS announces the 2027 amount in the fall.

➤ What are Part B excess charges?

Doctors who don’t accept Medicare assignment can charge up to 15% more than the Medicare-approved amount. Plan G covers that extra charge. Plan N does not, though most doctors accept assignment and some states ban excess charges.

➤ How much cheaper is Plan N than Plan G?

It varies by company, state, age and ZIP code. Plan N is usually noticeably cheaper each month. Compare real quotes for both plans from the same companies to see the gap where you live.

➤ Can I switch from Plan N to Plan G later?

You can apply, but outside your Medigap Open Enrollment Period or a guaranteed issue right, most states let insurance companies ask health questions and decline you. If you think you’ll want Plan G later, consider starting with it.

➤ Do Plan G and Plan N cover the same doctors?

Yes. Both work with any doctor or hospital in the United States that accepts Medicare. There are no networks and no referrals with either plan.

➤ Do Plan G and Plan N include drug coverage?

No. Neither plan includes prescription drug coverage. You need a separate Medicare Part D plan with either one.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Have Questions?

Speak with a licensed insurance agent

1-855-409-6195

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT