Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Medicare Supplement Plan N 2027

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 3, 2026

Medicare Supplement Plan N covers almost everything Plan G does for a lower monthly premium. In exchange, you pay small copays at the doctor’s office and emergency room, and Plan N doesn’t cover Part B excess charges.

Like every Medigap plan, Plan N is standardized by federal law. Plan N from one carrier pays exactly the same benefits as Plan N from any other, so the only thing that changes between companies is the price.

This guide covers what Plan N pays in 2027, what you still pay yourself, how it compares to Plan G, and how to tell whether the lower premium actually saves you money. For the full Plan G breakdown, see our Medicare Supplement Plan G 2027 guide.

Compare Medicare Supplement Plan N Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Deciding between the two most popular plans? See our full Plan G vs Plan N 2027 comparison, including the break-even math on premiums versus copays.

What Medicare Supplement Plan N Covers in 2027

Benefit Plan N pays 2026 amount
Part A hospital deductible 100% $1,736 per benefit period
Part A coinsurance and hospital costs 100% Plus 365 additional days
Skilled nursing facility coinsurance 100% Days 21–100
Part B coinsurance 100%, minus copays Up to $20 office, up to $50 ER
Foreign travel emergency 80% To plan limits, after deductible
Part B excess charges Not covered Up to 15% above Medicare’s rate
Part B annual deductible You pay $283 per year

The 2027 Part A and Part B amounts are announced in the fall. The 2026 Medicare Trustees Report projects a 2027 Part B deductible of $292. The structure of Plan N doesn’t change, only the dollar figures.

What You Pay With Plan N

Plan N leaves four costs to you. Only the last one is a monthly bill.

The Part B deductible — $283 in 2026. Once per calendar year, projected at $292 for 2027. Plan G leaves you the same deductible.
Office visit copays of up to $20. Charged on some doctor and specialist visits after you’ve met the Part B deductible.
Emergency room copays of up to $50. Waived if you’re admitted to the hospital as an inpatient.
Your Plan N premium. Set by the carrier, filed by state, and varying with your age, ZIP code and in most states tobacco use.

Plan N does not include prescription drug coverage. You’ll need a separate Part D plan, and for 2027 that plan carries a $2,400 annual out-of-pocket cap with a $700 standard deductible.

Plan N vs Plan G for 2027

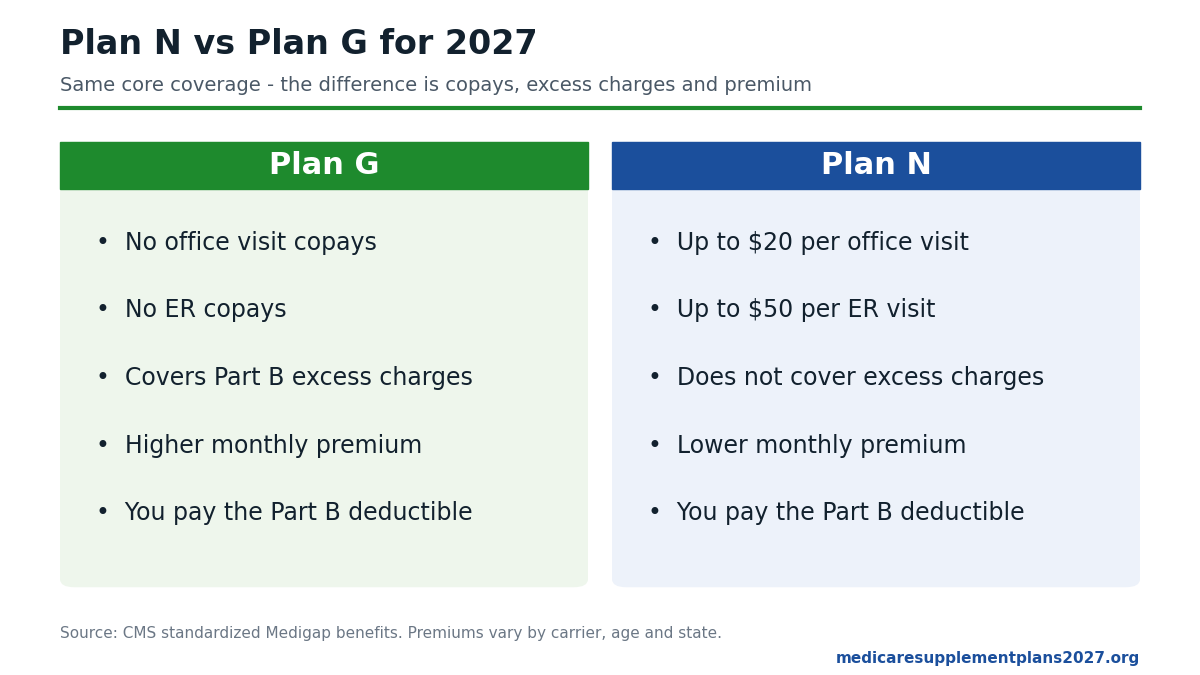
Plan G has no copays and covers excess charges, while Plan N charges up to $20 per office visit and $50 per ER visit for a lower premium

Plan N and Plan G are the two plans most people new to Medicare weigh against each other. They pay the same hospital, skilled nursing and coinsurance benefits. The differences come down to three things.

Factor Plan G Plan N
Office visit copay None Up to $20
Emergency room copay None Up to $50
Part B excess charges Covered Not covered
Monthly premium Higher Lower
Part B deductible You pay $283 You pay $283

If you see doctors often or live in a state where excess charges are common, Plan G is usually the safer buy. If you’re healthy and see a doctor a few times a year, Plan N’s lower premium often comes out ahead.

What Plan N Costs in 2027

Plan N premiums are filed carrier by carrier and state by state, and they vary with your age, your ZIP code and, in most states, tobacco use. Carriers are still filing 2027 rates. For 2026, MoneyGeek’s analysis puts Plan N at about $148 a month at age 65 under attained-age pricing, rising to about $267 a month at older ages.

Plan N is also subject to the same rate increase trend hitting Plan G. Plan G rate increases averaged 16.8% across the industry in 2026, and many carriers raise Plan N by similar amounts. See our breakdown of Medicare Supplement Plan G cost in 2027 for how age and pricing method change what you pay over time.

Because every Plan N pays the same benefits, the only meaningful comparison is Plan N against Plan N: same letter, same coverage, different price.

When Plan N Saves You Money

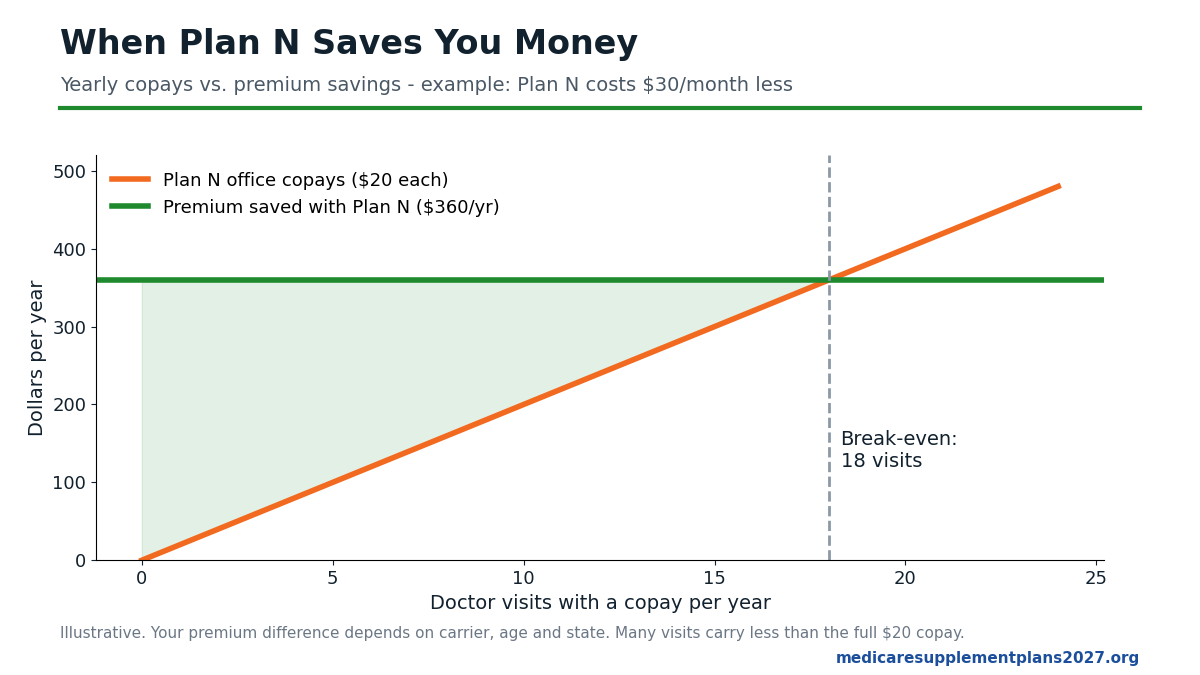
Plan N break-even example: at $30 a month in premium savings, Plan N stays cheaper than Plan G until about 18 office visits a year

The math is simple. Take the yearly premium you’d save choosing Plan N over Plan G, then compare it to the copays you’d expect to pay.

For example, if Plan N costs you $30 a month less than Plan G, you save $360 a year. At up to $20 per office visit, you’d need 18 copay visits in a year before Plan G comes out cheaper. Many visits carry less than the full $20, so the real break-even is often higher.

Plan N usually wins if you’re healthy, see a primary care doctor a few times a year and rarely visit the emergency room.
Plan G usually wins if you see specialists regularly, manage a chronic condition or simply want no copays at all.

Part B Excess Charges and Plan N

A doctor who doesn’t accept Medicare assignment can bill up to 15% above Medicare’s approved amount. That extra is called a Part B excess charge. Plan G covers it. Plan N does not.

In practice, most doctors accept assignment and never bill excess charges. Several states, including New York, Pennsylvania, Ohio, Massachusetts and Minnesota, limit or prohibit them altogether. Before choosing Plan N, check whether the doctors you see accept Medicare assignment.

Who Plan N Fits

Budget-focused and healthy. You want strong hospital and coinsurance protection while keeping your monthly premium down.
Comfortable with small copays. Paying up to $20 at the doctor’s office doesn’t bother you if it lowers your premium every month.
Doctors who accept assignment. Your providers accept Medicare’s approved amount, so excess charges aren’t a real risk for you.

Your Medigap Open Enrollment Period, the six months starting the month you’re 65 or older and enrolled in Part B, is the best time to buy Plan N. During it, carriers can’t use your health to deny coverage or charge you more. Enter your ZIP code above to compare 2027 Plan N rates from carriers licensed in your state.

Compare Medicare Supplement Plan N Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Medicare Supplement Plan N 2027 — Frequently Asked Questions

➤ What does Medicare Supplement Plan N cover?

Plan N covers the Part A hospital deductible, Part A coinsurance and hospital costs, skilled nursing facility coinsurance, Part B coinsurance except for copays of up to $20 for some office visits and up to $50 for emergency room visits, the first three pints of blood, hospice coinsurance and 80% of foreign travel emergency care. It does not cover the Part B deductible or Part B excess charges.

➤ How much does Plan N cost in 2027?

Carriers set 2027 Plan N rates through state filings, so there is no single national price. For 2026, MoneyGeek puts Plan N at about $148 a month at age 65 under attained-age pricing. Your actual premium depends on your age, ZIP code, carrier, pricing method and tobacco use.

➤ What are the Plan N copays?

Plan N charges up to $20 for some office visits and up to $50 for emergency room visits. The emergency room copay is waived if you are admitted to the hospital as an inpatient. You also pay the annual Part B deductible, which is $283 in 2026.

➤ Is Plan N better than Plan G?

It depends on how often you use care. Plan N has a lower premium but charges copays and doesn’t cover Part B excess charges. If the yearly premium you save with Plan N is larger than the copays you expect to pay, Plan N wins. If you see doctors often, Plan G usually costs less overall.

➤ Does Plan N cover Part B excess charges?

No. Plan N does not cover Part B excess charges, which a doctor who doesn’t accept Medicare assignment can bill up to 15% above Medicare’s approved amount. Most doctors accept assignment, and several states limit or prohibit excess charges.

➤ Does Plan N cover prescription drugs?

No. Medicare Supplement plans sold today do not include prescription drug coverage, so Plan N enrollees need a separate Part D plan. For 2027 the Part D annual out-of-pocket cap is $2,400 and the standard deductible is $700.
New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Have Questions?

Speak with a licensed insurance agent

1-855-409-6195

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT