Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Best Medicare Supplement Plans 2027: Top Plans and How to Choose

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 12, 2026

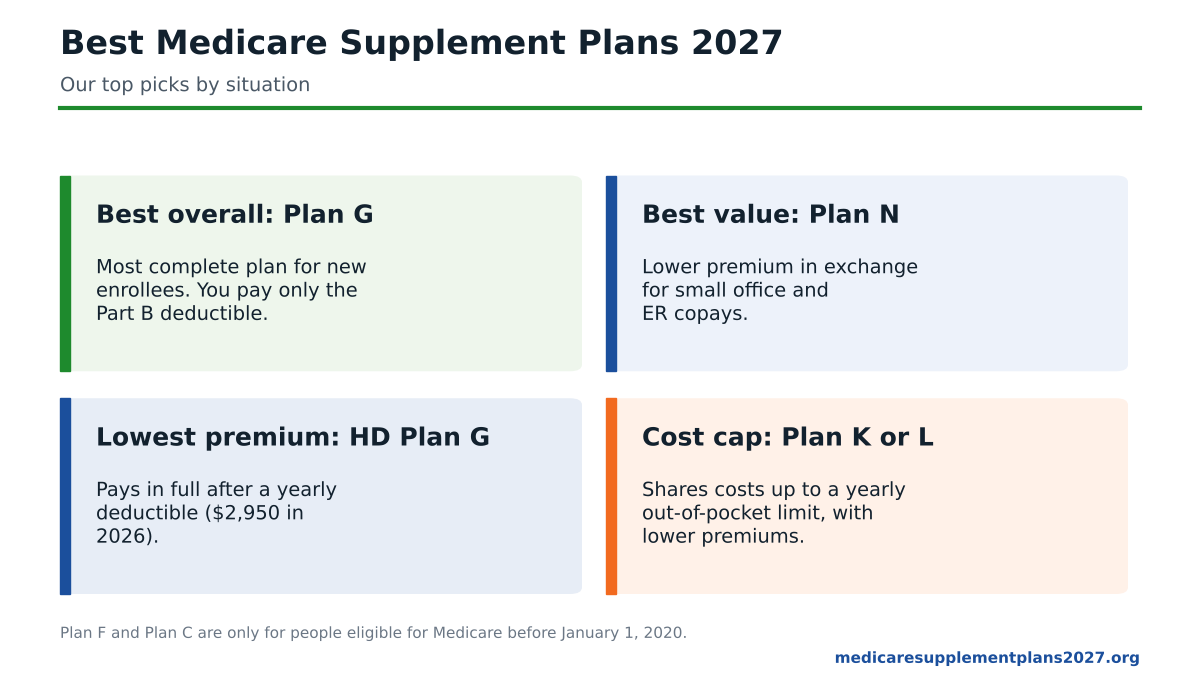
The best Medicare Supplement plan depends on how you use healthcare and how much risk you’re comfortable carrying. For most people new to Medicare in 2027, that comes down to four plans.

Here are our top picks by situation, followed by how to choose the best company for the plan you pick. Because Medigap benefits are standardized, the plan decides what’s covered and the company decides what you pay.
Not sure whether Medigap is the right path at all? See our side-by-side guide to Medicare Supplement vs Medicare Advantage 2027. It covers doctors, premiums, the 2027 out-of-pocket limit, and the rules for switching.

New to Medigap? Start with our step-by-step guide on How to Choose a Medigap Policy 2027, covering timing, plan letters, pricing methods and the mistakes to avoid.

Compare the Best Medicare Supplement Plans for 2027

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Best Medicare Supplement plans 2027 top picks: Plan G, Plan N, High Deductible Plan G and Plan K or L

The Best Medicare Supplement Plans for 2027

Pick Plan What You Pay
Best overall Plan G The Part B deductible ($283 in 2026)
Best value Plan N Part B deductible, up to $20 office and $50 ER copays
Lowest premium High Deductible Plan G A yearly deductible ($2,950 in 2026), then nothing
Best for a cost cap Plan K or Plan L A share of costs up to $8,000 (K) or $4,000 (L) in 2026

To see every benefit each plan pays side by side, use our Medicare Supplement plans comparison chart for 2027.

Best Overall: Plan G

Plan G is the most complete Medigap plan available to anyone new to Medicare. After the Part B deductible, it pays your Medicare-approved costs in full, including the Part A hospital deductible, coinsurance and Part B excess charges.

That makes your yearly costs predictable: your premium plus one deductible. See our full guide to Medicare Supplement Plan G for 2027 and the Medicare Plan G deductible for 2027.

Best Value: Plan N

Plan N covers almost everything Plan G does at a lower premium. The trade is copays of up to $20 for some office visits and up to $50 for ER visits that don’t result in admission, and no coverage for Part B excess charges.

If you’re healthy and see the doctor a few times a year, the premium savings often outweigh the copays. See our Medicare Supplement Plan N 2027 guide.

Compare the Best Medicare Supplement Plans for 2027

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Lowest Premium: High Deductible Plan G

High Deductible Plan G has the lowest premium of the popular plans. You pay Medicare-covered costs until you reach a yearly deductible, $2,950 in 2026, and then it pays exactly what regular Plan G pays.

It fits people who rarely see a doctor but want protection from a big hospital bill, and who can set aside the deductible if they need it.

Best for a Cost Cap: Plan K or Plan L

Plans K and L pay a share of most costs, 50% and 75%, until you reach a yearly out-of-pocket limit. In 2026 the limits were $8,000 for Plan K and $4,000 for Plan L. After that, the plan pays 100% for the rest of the year.

Premiums are lower than Plan G, but your costs in a heavy-use year are higher. They suit people who want a lower premium with a firm ceiling on what they’ll spend.

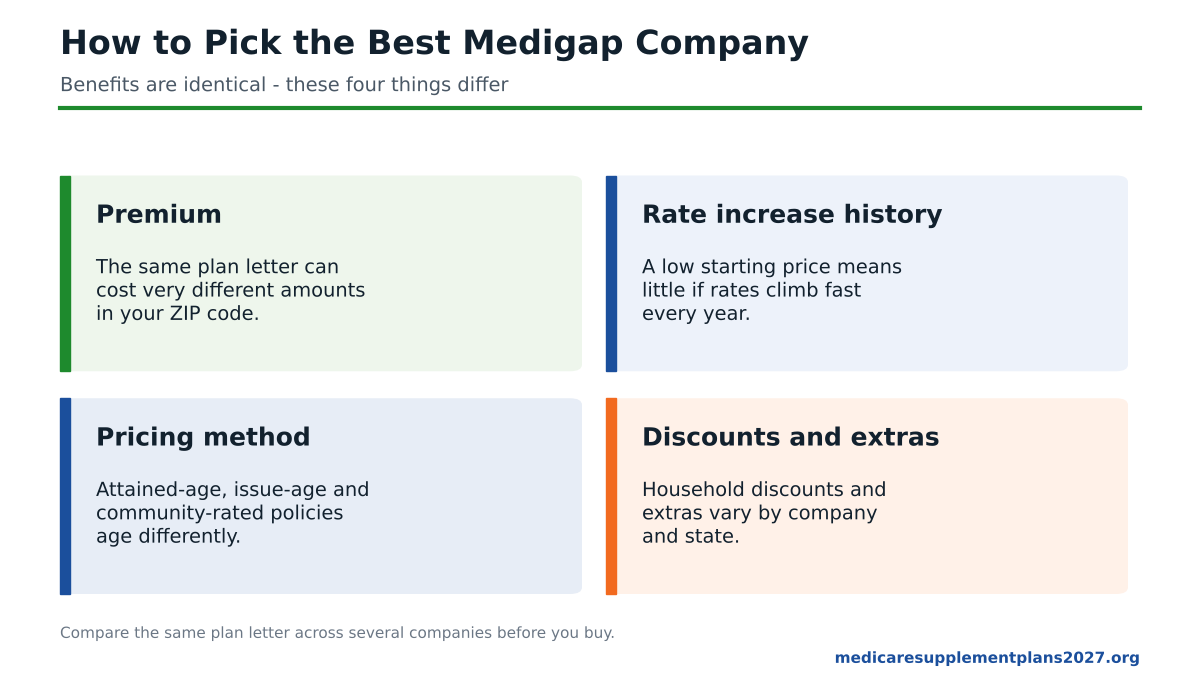
How to choose the best Medicare Supplement company in 2027 by premium, rate history, pricing method and discounts

How to Choose the Best Medicare Supplement Company

Every company’s Plan G pays the same benefits, so the best company is the one that gives you the best price over time. Compare these four things:

  • Premium. The same letter can cost very different amounts in the same ZIP code.
  • Rate increase history. Plan G rate increases averaged 16.8% across the industry in 2026, according to Telos Actuarial. A low starting price means little if rates climb fast.
  • Pricing method. Attained-age, issue-age and community-rated policies age very differently.
  • Discounts and extras. Household discounts and extras vary by company and state.

Large national carriers worth comparing include UnitedHealthcare Medicare Supplement plans, Aetna Medicare Supplement plans and Blue Cross Blue Shield Medicare Supplement plans. See what Plan G typically runs in our Medicare Supplement Plan G cost 2027 breakdown.

Want to know how the top carriers stack up? See our Medicare Supplement Reviews 2027, comparing financial strength, discounts and rate history across leading Medigap companies.

Before You Enroll: 2027 Checklist

  1. Pick your plan. Plan G for the most coverage, Plan N for value, High Deductible G for the lowest premium.
  2. Check your timing. Your Medigap Open Enrollment Period gives you guaranteed acceptance.
  3. Compare the same letter across carriers. Benefits are identical, so price is the difference.
  4. Ask about rate history and pricing method. They decide what you’ll pay in five years.
  5. Ask about discounts. Household and payment discounts can lower your premium.
  6. Add a Part D plan. Compare all Medicare Supplement plans for 2027 alongside your drug coverage.

Related: Bankers Fidelity Medicare Supplement plans for 2027 Our review of its rating, household discount and where it sells.

Best Medicare Supplement Plans for 2027: Compare Rates & Benefits

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Best Medicare Supplement Plans 2027 — Frequently Asked Questions

➤ What is the best Medicare Supplement plan for 2027?

For most people new to Medicare, Plan G is the best overall Medicare Supplement plan. It covers everything Original Medicare leaves behind except the Part B deductible, which was $283 in 2026.

➤ Is Plan G or Plan N better?

Plan G is more complete. Plan N usually costs less but adds copays of up to $20 for some office visits and up to $50 for ER visits, and it doesn’t cover Part B excess charges. If you see doctors often, Plan G is usually the better value.

➤ What is the cheapest Medicare Supplement plan?

High Deductible Plan G usually has the lowest premium of the popular plans. You pay Medicare-covered costs up to a yearly deductible, $2,950 in 2026, and after that it pays the same as regular Plan G.

➤ Which company has the best Medicare Supplement plans?

There is no single best company everywhere. Medigap benefits are identical across carriers, so the best company is the one with a competitive premium, a steady rate increase history and the discounts you qualify for in your ZIP code. Compare several before you buy.

➤ Is Plan F still the best Medicare Supplement plan?

Plan F is only available to people eligible for Medicare before January 1, 2020. For everyone else, Plan G is the most complete option, covering everything Plan F does except the Part B deductible.

➤ Do the best Medicare Supplement plans include drug coverage?

No. No Medigap plan sold today includes prescription drug coverage. You need a separate Medicare Part D plan alongside your Medicare Supplement plan.

➤ When is the best time to buy a Medicare Supplement plan?

Your Medigap Open Enrollment Period, the six months starting the month you are 65 or older and enrolled in Part B. During that window, insurance companies can’t deny you coverage or charge you more because of your health.

➤ Can I change Medicare Supplement plans later?

You can apply to change plans at any time, but outside your Medigap Open Enrollment Period or a guaranteed issue right, most states let insurance companies ask health questions and decline you. That makes choosing the right plan up front important.