Speak with a licensed insurance agent
1-855-409-6195
TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 14, 2026
The Medigap Open Enrollment Period is the most important date on your Medicare calendar, and most people don’t know it exists. It’s a one-time window when any carrier has to sell you a Medicare Supplement plan, whatever your health. Miss it, and getting a Medigap plan later can mean health questions, higher rates, or a flat no.
Here’s how the window works in 2027, when yours starts, and what to do if you’ve already missed it.
Confused by the fall enrollment window? See Medicare Open Enrollment 2027 for the October 15 to December 7 dates and what they mean for Medicare Supplement plans.
How the Medigap Open Enrollment Period Works
Compare 2027 Medicare Supplement Rates
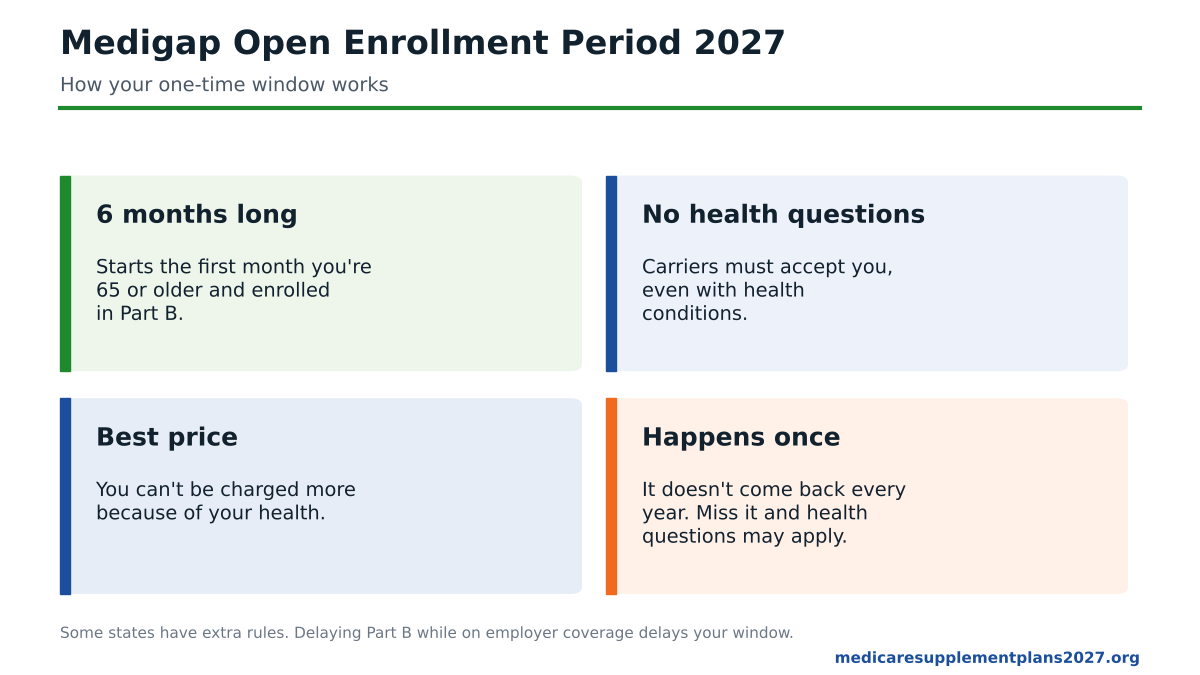
Your window: 6 months, starting the first month you are both 65 or older and enrolled in Medicare Part B. It happens once and does not renew every year.
During those 6 months, you get guaranteed acceptance:
- A carrier must sell you any Medigap plan it offers in your state.
- It can’t ask health questions to turn you down.
- It can’t charge you more because of your health. You get the same price as someone in perfect health.
That’s why this is the best time to lock in a plan like Plan G or Plan N.
When Does Your Window Start?
| Your situation | When your Medigap window starts |
|---|---|
| You turn 65 and start Part B the month you turn 65 | The first day of the month you turn 65 (when Part B starts) |
| You delay Part B because you’re still working with employer coverage | The month your Part B starts, whenever you sign up |
| You’re under 65 on Medicare due to disability | Depends on your state; you get a new window when you turn 65 |
Your window ends 6 months after it starts. Applying a few months early is fine. Many carriers accept applications up to 6 months before your Part B start date.
Medigap Open Enrollment vs the Fall Annual Enrollment Period
This trips up a lot of people. The Annual Enrollment Period (October 15 to December 7) is for Medicare Advantage and Part D drug plans. It is not a Medigap enrollment period.
You can apply for a Medigap plan any day of the year. Outside your one-time Medigap Open Enrollment Period, though, most carriers can ask health questions and decide whether to accept you. There’s no fall “reset” that gives you guaranteed acceptance again.
See 2027 Medigap Rates in Your ZIP Code
Pre-Existing Condition Waiting Periods
Even during open enrollment, a carrier can sometimes make you wait up to 6 months before it covers a pre-existing condition. That only applies if you didn’t have creditable health coverage for at least 6 months before you enrolled.
If you’re coming off employer coverage or another qualifying plan with no long gap, that wait is usually shortened or removed altogether.
Missed Your Window? Other Ways In
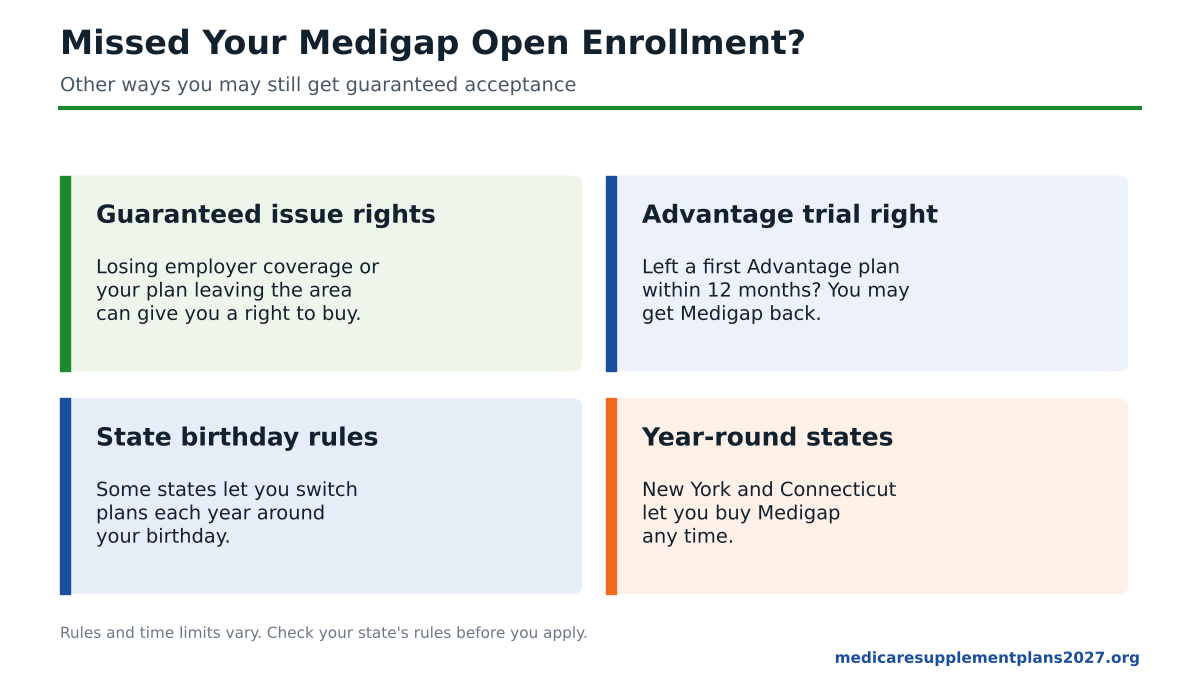
If your 6 months have passed, you still have options:
- Federal guaranteed issue rights. Certain events give you the right to buy specific Medigap plans without health questions, for example losing employer group coverage or your Medicare Advantage plan leaving your area. Time limits apply, usually 63 days.
- The Medicare Advantage trial right. If you joined Medicare Advantage when you first got Medicare and leave within 12 months, you can usually go back to Original Medicare and buy a Medigap plan with no health questions.
- State birthday and anniversary rules. Several states let you switch to a Medigap plan with equal or lesser benefits each year around your birthday or policy anniversary.
- Year-round states. New York and Connecticut let you buy a Medigap plan any time without health questions.
- Apply with underwriting. If you’re in good health, you may simply pass the carrier’s health questions. Rules and questions vary by carrier.
Medigap or Medicare Advantage: Decide Before Your Window Closes
Many people pick a $0 Medicare Advantage plan at 65 and find out years later that getting a Medigap plan isn’t guaranteed anymore. If there’s any chance you’ll want Medigap’s freedom to see any doctor, your open enrollment window is the time to get it.
Compare both paths in our Medicare Supplement vs Medicare Advantage 2027 guide, and see every plan side by side in the Medicare Supplement plans comparison chart 2027.
Related: Can you change Medicare Supplement plans later? Rules for switching after open enrollment, birthday rule states and how to avoid a gap.
Compare 2027 Medicare Supplement Rates & Benefits
Medigap Open Enrollment Period FAQs
➤ When is the Medigap Open Enrollment Period?
Your Medigap Open Enrollment Period is a one-time, 6-month window. It starts the first month you are both 65 or older and enrolled in Medicare Part B.
➤ Is there a Medigap open enrollment every year?
No. The Medigap Open Enrollment Period happens once. The fall Annual Enrollment Period from October 15 to December 7 is for Medicare Advantage and Part D drug plans, not Medigap. You can apply for a Medigap plan any time of year, but outside your open enrollment window, carriers can usually ask health questions.
➤ Can I be turned down for a Medigap plan during open enrollment?
No. During your Medigap Open Enrollment Period, carriers must sell you any Medigap plan they offer in your state, and they can’t charge you more because of your health.
➤ Can there be a waiting period for pre-existing conditions?
Possibly. If you didn’t have creditable health coverage for at least 6 months before you enrolled, a carrier can delay coverage of a pre-existing condition for up to 6 months. Prior creditable coverage reduces or removes that wait.
➤ What happens if I miss my Medigap Open Enrollment Period?
You can still apply, but most carriers can ask health questions and may decline you or charge more. You may still have guaranteed acceptance through a federal guaranteed issue right, the Medicare Advantage trial right, or your state’s rules.
➤ What are Medigap guaranteed issue rights?
Guaranteed issue rights let you buy certain Medigap plans without health questions in specific situations, such as losing employer group coverage, your Medicare Advantage plan leaving your area, or leaving a Medicare Advantage plan within 12 months of first joining. Time limits apply.
➤ Does working past 65 affect my Medigap Open Enrollment Period?
Yes. Your window doesn’t start until you enroll in Part B. If you delay Part B because you have employer coverage from current work, your Medigap Open Enrollment Period starts later, when you sign up for Part B.
➤ Which states let you change Medigap plans more easily?
New York and Connecticut let you buy a Medigap plan any time of year without health questions. Several other states have birthday or anniversary rules that let you switch to a plan with equal or lesser benefits each year. Rules vary by state.
New to Medicare?
If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.
Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.
Compare plans & benefits in your area
Or speak with a licensed insurance agent
1-855-409-6195TTY 711
Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT