Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Cheapest Medicare Supplement Plans 2027: Low-Cost Plan Letters and How to Find the Best Rate

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

The cheapest Medicare Supplement plans are usually High-Deductible Plan G, Plan K and Plan N, with Plan A as a basic option. Each one keeps the premium low by leaving more costs to you, and the same plan letter can cost very different amounts from one company to the next.

A low premium is only half the story. A plan that costs less each month can cost more over the year if you need a lot of care. The best cheap plan is the one whose gaps you can afford.

This guide shows which plan letters cost the least, what you give up with each, and why prices for the same plan vary so much. For a full breakdown of what drives premiums, see our guide to Medicare Supplement plans cost.
Compare the Cheapest 2027 Medicare Supplement Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

The Cheapest Medicare Supplement Plan Letters

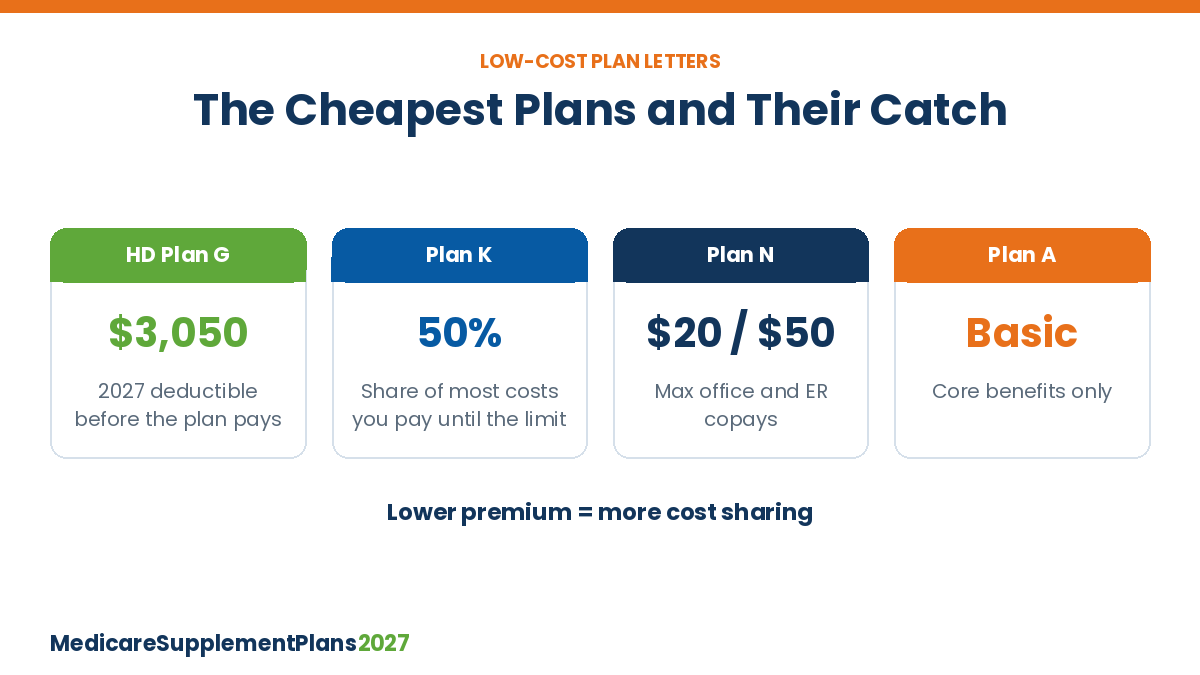
Cheapest Medicare Supplement plans for 2027: High-Deductible Plan G, Plan K, Plan N and Plan A

Medicare Supplement plans are standardized in most states. A Plan N from one company has the same benefits as a Plan N from another. The lower-cost letters are the ones that share more of the bill with you.

Plan What you give up Best for
High-Deductible Plan G You pay a $3,050 deductible in 2027 before the plan pays Healthy people who want big-bill protection
Plan K Pays 50% of most costs until you reach the yearly out-of-pocket limit People who want a cap but a low premium
Plan N Copays of up to $20 for some office visits and up to $50 for ER visits that do not lead to admission; no excess charge coverage Healthy people who see doctors who accept Medicare
Plan A Basic benefits only; no Part A deductible coverage People with few other options, such as some under 65

Plan benefits from Medicare.gov. The 2027 high-deductible amount is set by CMS. Plans are standardized differently in Massachusetts, Minnesota and Wisconsin.

Broker tip: Plan A is not always cheaper than Plan N. In many areas the gap is small, and Plan N covers much more.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

No obligation to enroll

The Trade-Offs of a Low Premium

High-Deductible Plan G. Your worst-case year is the $3,050 deductible plus your premiums. After that, the plan covers what regular Plan G covers. Learn more on our High-Deductible Plan G page.

Plan K. The 2026 out-of-pocket limit is $8,000. Plan L, a step up, has a $4,000 limit. After you reach the limit and the Part B deductible, the plan pays 100%.

Plan N. Small copays add up if you see doctors often. You also pay the Part B deductible, which is $283 in 2026. See our Plan N guide.

A simple test: add the yearly premium to the most you could owe out of pocket. Compare that total, not just the monthly price, against Plan G.

If you have ongoing health problems or see specialists often, the cheapest plan on paper may not save you money. Copays, a high deductible or 50% cost sharing can wipe out the premium savings in a single bad year. If you are healthy and have savings to cover a surprise bill, a low-cost plan can keep more money in your pocket year after year.

Why the Same Plan Costs Different Amounts

Because benefits are the same, the price is the main thing that changes between companies. Each company sets its own rates and files them with the state.

Where you live. Rates are set by ZIP code or region, so prices differ even within one state.

Your age, gender and tobacco use. Most companies charge more for older buyers and tobacco users.

The company’s claims history. A company with higher claims costs may raise rates faster.

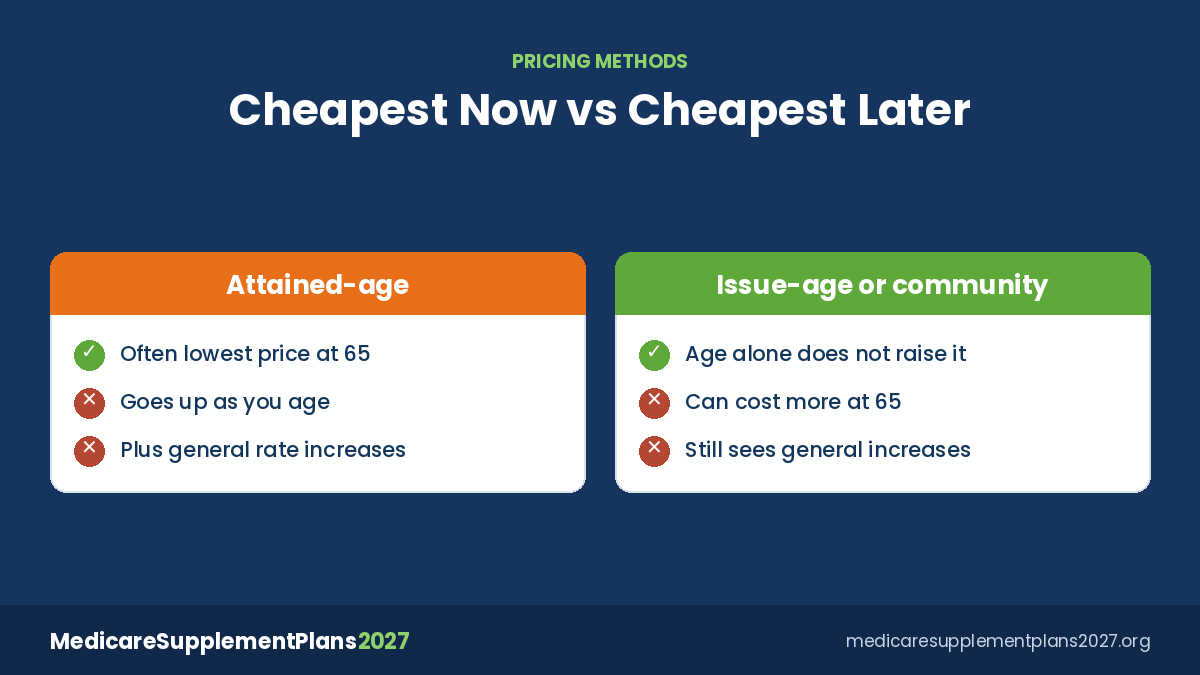
How the company prices its plans. Community, issue-age and attained-age pricing work very differently over time.

This is why two neighbors with the same plan letter can pay very different premiums. Shopping several companies for the exact same benefits is the easiest way to save, because you give up nothing in coverage. Your doctors do not change either. Any doctor who accepts Medicare accepts every Medicare Supplement plan.

Pricing Methods: Why the Cheapest Today May Not Stay Cheapest

Cheapest Medicare Supplement plans pricing: attained-age versus issue-age rates over time
Method How it works What to expect
Community-rated Everyone pays the same premium no matter their age Can cost more at 65, but age alone does not raise it
Issue-age-rated Premium is based on your age when you buy Does not go up because you age, but can rise for inflation and other reasons
Attained-age-rated Premium is based on your current age Often lowest at 65, then goes up as you get older

Pricing methods as described by Medicare.gov. Every method can still see rate increases for inflation and claims costs. Which methods are sold depends on your state and the company.

The lowest quote at 65 is often an attained-age plan. That does not make it a bad choice, but it does mean the price will climb with age on top of any general increases. Read our page on Plan G rate increases to see how increases work.

Ask before you buy: Ask how the plan is priced and what its recent rate history looks like. A slightly higher price from a steady company can cost less over 10 years.

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Household and Other Discounts

Discounts can turn a middle-priced plan into the cheapest one. They vary by company and state, so always ask what applies.

Household discount. Many companies offer a lower rate if you live with a spouse or another adult. Some require both people to buy from the same company.

Payment discounts. Some companies lower the rate if you pay by bank draft or pay for the year up front.

Non-tobacco rate. If you do not use tobacco, make sure you are quoted the non-tobacco rate.

Household discounts often matter most for couples. If one spouse turns 65 first, ask whether the discount still applies when only one of you has a policy with that company.

Broker tip: Compare quotes with and without the household discount. The cheapest base rate is not always the cheapest after discounts.

How to Find the Lowest Rate

1

Choose the plan letter first. Decide which gaps you can afford, then shop that letter.

2

Get quotes from several companies. Compare the same plan letter in your ZIP code side by side.

3

Check the pricing method. Know whether the rate is community, issue-age or attained-age.

4

Apply every discount. Ask about household, payment and non-tobacco rates.

5

Buy during a protected window if you can. In your open enrollment period you get the best rate with no health questions.

If you are leaning toward Plan G, our Medicare Supplement Plan G cost guide shows how to weigh it against the cheaper letters.

Bottom Line

The cheapest Medicare Supplement plans keep premiums low by leaving more of the bill to you, so pick the plan letter whose gaps you can afford first. Then compare that same letter across companies, check how each one prices its plans, and apply every discount before you choose.

View 2027 plans & rates in your ZIP code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Cheapest Medicare Supplement Plans — Frequently Asked Questions

➤ What is the cheapest Medicare Supplement plan?

High-Deductible Plan G and Plan K usually have the lowest premiums, followed by Plan N. The exact cheapest plan depends on your ZIP code, age and the companies in your area.

➤ What is the High-Deductible Plan G deductible for 2027?

It is $3,050 in 2027. You pay Medicare-covered costs up to that amount before the plan starts paying.

➤ What is the Plan K out-of-pocket limit?

The 2026 limit is $8,000. After you reach it and pay the Part B deductible, Plan K pays 100% of covered costs for the rest of the year.

➤ Is Plan N cheaper than Plan G?

Plan N usually costs less per month than Plan G. In exchange, you pay small copays for some visits, the Part B deductible and any excess charges.

➤ Why does the same plan cost more with one company?

Benefits are the same, but each company sets its own rates based on its pricing method, claims costs and where you live.

➤ Is the cheapest plan at 65 the best choice?

Not always. An attained-age plan can be cheapest at 65 but rise as you age. Look at the company’s pricing method and rate history too.

➤ Do Medicare Supplement plans offer household discounts?

Many companies do if you live with a spouse or another adult. The rules and amounts differ by company and state.

➤ Can I switch to a cheaper plan later?

Yes, you can apply at any time. Outside your open enrollment period or a guaranteed issue right, most states let the company ask health questions.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

No obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT