Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Medicare Supplement Plan L 2027: 75% Coverage, the $4,180 Cap and the Real Math

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 1, 2026

Medicare Supplement Plan L pays 75% of most Medicare cost sharing, pays hospital coinsurance in full, and stops your share at $4,180 for 2027. After you reach that CMS limit and pay the Part B deductible, Plan L pays 100% of covered costs until December 31.

2027 by the Numbers

$4,180

2027 Plan L out-of-pocket limit (CMS)

$8,360

2027 Plan K limit, exactly double (CMS)

75%

share of most cost sharing Plan L pays (Medicare.gov)

$434

your 25% of the 2026 Part A deductible of $1,736

Plan L sits in the middle of the plan letters. It leaves you a quarter of most bills, which keeps the premium below the fuller plans in many areas, yet it still gives you a hard ceiling on a bad year. Fewer companies sell it than Plan G or Plan N, so many shoppers never see it on a quote.

Below you will find what Plan L pays, how its 2027 cap works, a dollar-by-dollar example, and where it fits next to Medicare Supplement Plan K and Plan G.
Compare 2027 Medicare Supplement Plan L Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

What Plan L Pays: 75% of Most Bills, 100% of Long Hospital Stays

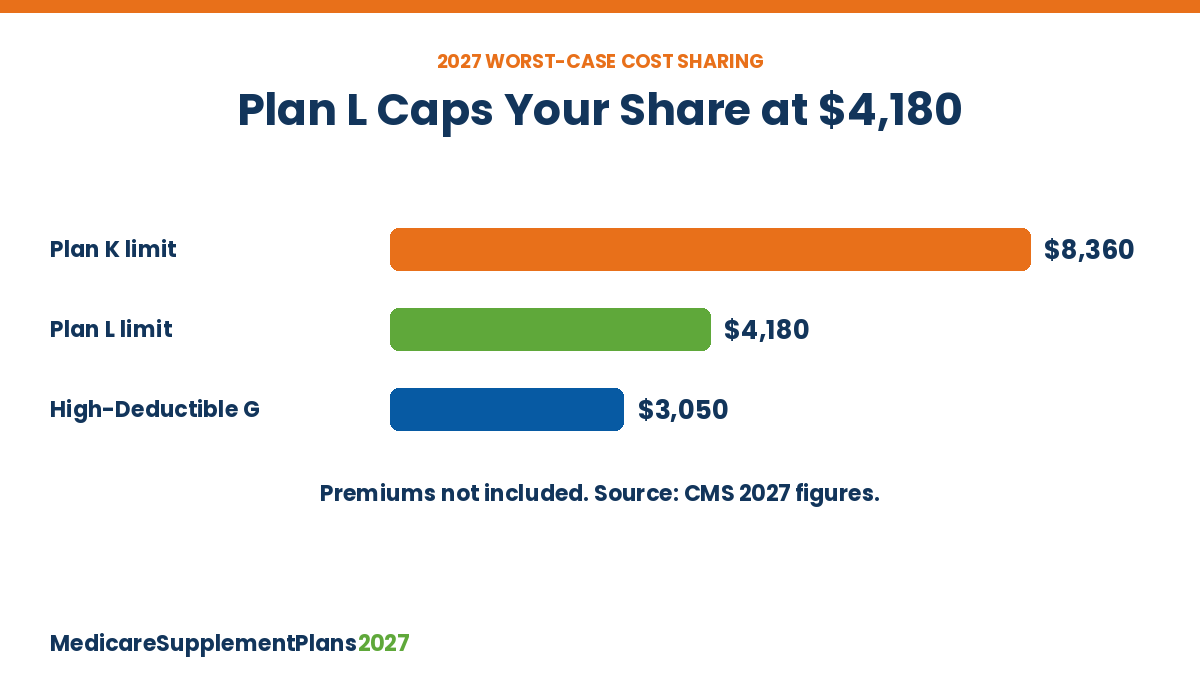
Medicare Supplement Plan L 2027 out-of-pocket cap of $4,180 compared with Plan K and High-Deductible Plan G

Plan L is standardized by federal law. That means a Plan L from one insurer pays exactly the same benefits as a Plan L from another. Only the price, the customer service and the rate history differ.

Medicare cost Plan L share Your share before the cap
Part A hospital coinsurance and 365 more days after Medicare runs out 100% $0
Part A deductible (per benefit period) 75% 25%
Part B coinsurance and copays 75% 25%
Skilled nursing facility coinsurance 75% 25%
Part A hospice coinsurance and copays 75% 25%
First 3 pints of blood 75% 25%
Part B deductible 0% 100%
Part B excess charges 0% 100%
Emergency care outside the U.S. 0% 100%

Benefits from Medicare.gov. Massachusetts, Minnesota and Wisconsin use their own plan designs and do not sell a lettered Plan L.

Good to know: Some online guides list a 95% Part B benefit or 100% hospice benefit for Plan L. The federal standard is 75% for both until you reach the yearly limit.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711  |  Mon–Fri: 5am–7pm, Sat–Sun: 7am–4pm CT

No obligation to enroll

The Plan L Cap for 2027 and How It Has Grown

CMS adjusts the Plan L limit each fall for the next calendar year. It started at $2,000 in 2006 and rises with Medicare spending, so the figure on an older brochure is likely out of date.

Calendar year Plan L limit Change from prior year
2025 $3,610 —
2026 $4,000 +$390
2027 $4,180 +$180

Source: CMS Plan K and L out-of-pocket limit announcements; 2025 figure as published by carriers.

Counts toward the cap. Your 25% share of covered costs, such as a quarter of the Part A deductible and a quarter of Part B coinsurance.

Never counts. Monthly premiums and Part B excess charges. You keep paying both even after the cap.

Ask about the Part B deductible. You must pay it before the plan reaches 100%. Your policy outline shows exactly how it is treated.

One Year, Three Plans: A Worked Cost Example

Picture one hospital admission plus $10,000 in Medicare-approved outpatient care, such as scans and specialist visits. The math below uses 2026 Medicare figures, since CMS has not yet set the 2027 Part A deductible. Premiums are left out.

Your cost Plan L Plan K Plan G
Part A deductible ($1,736) $434 $868 $0
Part B deductible $283 $283 $283
Part B coinsurance (20% of $9,717 = $1,943) $486 $972 $0
Total you pay $1,203 $2,123 $283

Our calculation from 2026 Medicare figures (Part A deductible $1,736, Part B deductible $283). Figures rounded to the dollar.

Plan L cuts this year’s bill by about $920 compared with Plan K. Plan G cuts it by another $920 or so. Whether either upgrade is worth it depends on how much more the premium costs in your ZIP code, so get real quotes for all three. Our Plan G guide covers that plan in detail.

Quick test: Take the yearly premium gap between Plan L and Plan G. If your expected 25% share is smaller than that gap, Plan L comes out ahead that year.

When the Plan L Cap Actually Kicks In

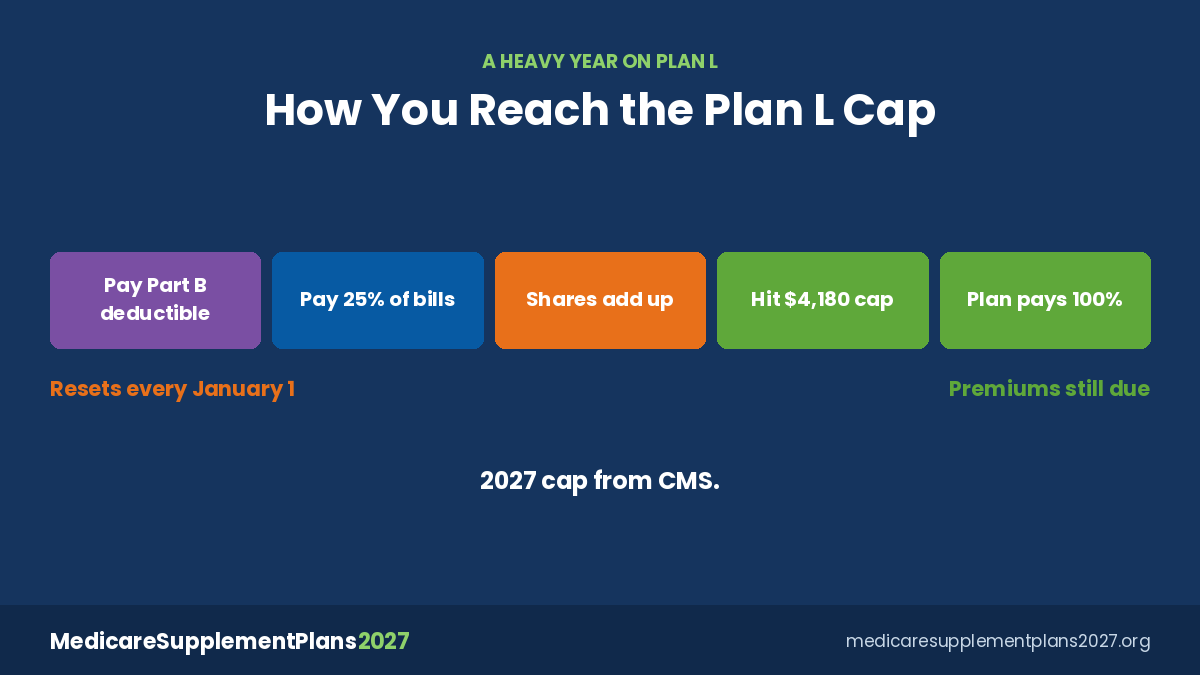
How a heavy year on Medicare Supplement Plan L builds toward the 2027 out-of-pocket cap

Because Plan L pays 75%, your share grows slowly. Using 2026 figures and one hospital stay, you would need roughly $71,000 in Medicare-approved Part B charges in a single year before your share reached the $4,000 cap. That is the kind of year that comes with cancer treatment, dialysis or a major surgery with long follow-up.

Same trigger point as Plan K. Plan K pays half as much but its cap is twice as high. Run the numbers and both plans hit their caps at about the same level of spending.

What differs is the size of the bill. At that point a Plan L member has paid about $4,000. A Plan K member has paid about $8,000 for the same care.

Multiple hospital stays speed it up. Each new benefit period brings another Part A deductible, and your 25% of each one counts toward the cap.

In a light year, the cap never matters. In a heavy year, it is the feature that protects your savings.

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

Why Few Companies Sell Plan L

Insurers do not have to offer every letter. Most focus on Plan G, Plan N and High-Deductible Plan G, which is why Plan L rarely shows up on quote lists. Humana and some Blue Cross Blue Shield companies, such as Blue Cross Blue Shield of North Dakota, list Plan L, but availability changes by state and county.

Fewer buyers, fewer sellers. A small enrollment pool means fewer companies file Plan L rates, so you may only see one or two prices.

Three states are different. Massachusetts, Minnesota and Wisconsin have their own standardized plans, so Plan L is not sold there.

Rate history matters more. With few choices, look at how often a company has raised Plan L rates before you buy.

If no company offers Plan L near you, High-Deductible Plan G is the closest option with a fixed worst case. Its 2027 deductible is $3,050, and it also covers excess charges and foreign travel emergencies.

Is Plan L Right for You? A Four-Question Check

1

Could you pay $4,180 in a bad year? If that amount would not wreck your budget, Plan L’s cost sharing is manageable.

2

Do your doctors accept Medicare assignment? Plan L never pays excess charges, so it works best when your doctors take the Medicare-approved amount.

3

Do you travel abroad often? Plan L has no foreign travel emergency benefit. Plan G and Plan N do.

4

Are you inside your open enrollment window? During your six-month Medigap Open Enrollment Period, a company cannot deny you or charge more for health problems. Later, it usually can.

Plan L tends to suit people in fair to good health who want more help than Plan K gives but do not want to pay for full coverage. To line it up against every other letter, open our Medicare Supplement plans comparison chart.

Bottom Line

Medicare Supplement Plan L leaves you 25% of most costs and caps that share at $4,180 for 2027, half of Plan K’s cap. It can make sense if you want a known ceiling and a lower premium than Plan G, but few companies sell it. Price Plan L, Plan G and High-Deductible Plan G side by side in your ZIP code before you decide.

See which companies offer Plan L in your ZIP code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

Medicare Supplement Plan L — Frequently Asked Questions

➤ What is the Plan L out-of-pocket limit in 2027?

CMS set it at $4,180 for 2027, up from $4,000 in 2026. Once your share of covered costs reaches it and you have paid the Part B deductible, Plan L pays 100% for the rest of the year.

➤ How much of the Part A deductible does Plan L pay?

Plan L pays 75% of the Part A deductible. In 2026 the deductible is $1,736, so your 25% share is $434 for each benefit period.

➤ Does Plan L pay my share at the doctor’s office?

It pays 75% of Part B coinsurance after you meet the Part B deductible. You pay the other 25% until you reach the yearly cap.

➤ Is Medicare Plan L the same as Medicare Supplement Plan L?

Yes. People often say Medicare Plan L, but it is a Medicare Supplement plan sold by private insurers. It is not the same as Medicare Part A or Part B.

➤ Why can’t I find Plan L on most quote sites?

Only some insurers choose to sell Plan L, and many states have just a few sellers. If no one offers it in your ZIP code, compare Plan K or High-Deductible Plan G instead.

➤ Can I switch from Plan L to Plan G later?

You can apply at any time, but outside your open enrollment window or a guaranteed issue situation the company can review your health and may say no. Some states give extra switching rights.

➤ Does Plan L cover hospice care?

Yes. Plan L pays 75% of Part A hospice coinsurance and copays until you reach the yearly cap, then 100%.

➤ Is Plan L sold in Massachusetts, Minnesota or Wisconsin?

No. Those three states use their own standardized plan designs instead of the lettered plans, so Plan L is not offered there.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711  |  Mon–Fri: 5am–7pm, Sat–Sun: 7am–4pm CT

No obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent