Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Medicare Supplement Plan A 2027: Who Should Buy It, Real Costs and Guaranteed Issue

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 30, 2026

Medicare Supplement Plan A is the basic plan every Medicare Supplement company must sell: it pays your Part A hospital coinsurance, 365 extra hospital days, Part B coinsurance, the first 3 pints of blood and hospice coinsurance, but not the $1,736 Part A deductible. It makes the most sense when it is the only plan you can get without health questions, such as under 65 in some states.

2027 by the Numbers

$1,736

2026 Part A deductible per benefit period that Plan A does not pay (CMS)

$283

2026 Part B deductible you pay with Plan A (CMS); $292 projected for 2027 (Trustees)

365

extra lifetime hospital days Plan A pays after Medicare days run out (Medicare.gov)

Plan A is the smallest standardized Medicare Supplement plan and the one letter every company has to offer. Few people choose it on purpose. Most use it as a door into coverage when a richer plan would mean health questions.

Below we show what Plan A leaves you paying, with our own dollar math, how its premium compares with Plan G and Plan N, and when it is the smart pick. To see every letter on one page, open our Medicare Supplement plans comparison chart.
Compare 2027 Medicare Supplement Plan A Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

Plan A's Four Core Benefits and the Gaps It Leaves Open

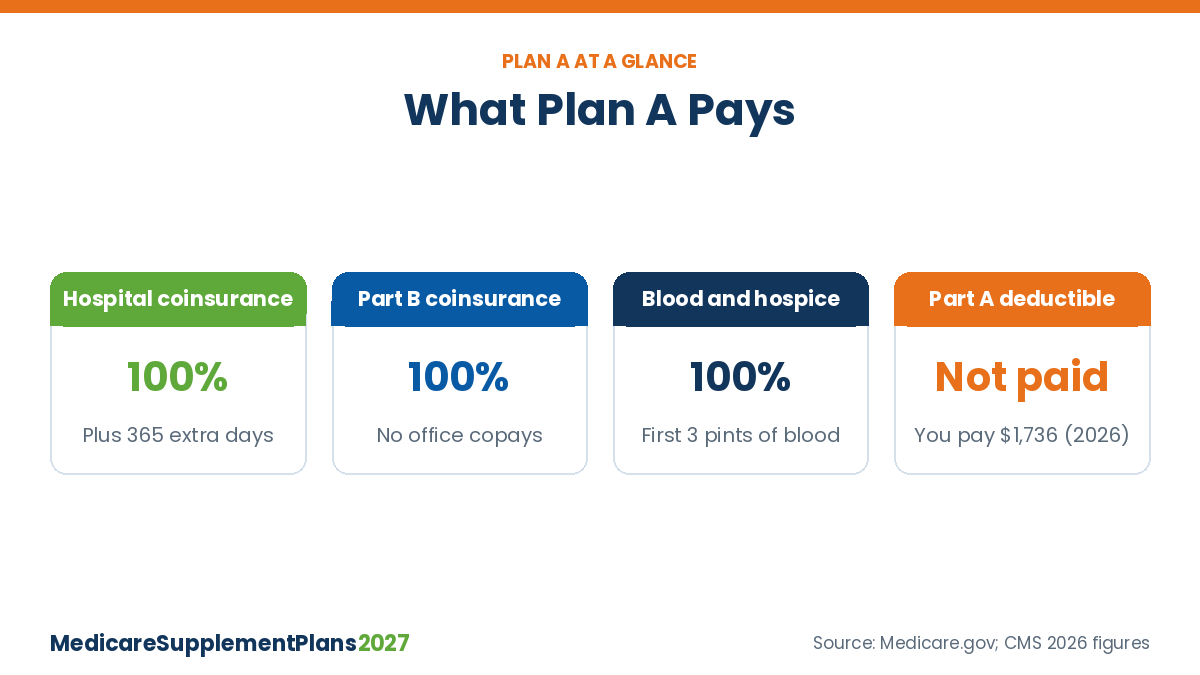
Medicare Supplement Plan A 2027 benefits: 100% of hospital and Part B coinsurance, 365 extra hospital days, but not the $1,736 Part A deductible

Because Plan A is standardized, a policy from one company pays the same benefits as Plan A from any other. Only the price and service differ.

Medicare cost Plan A What you pay
Part A hospital coinsurance, plus 365 more hospital days after Medicare days are used Pays 100% $0
Part B coinsurance or copayment (usually 20%) Pays 100% $0, no office copays
First 3 pints of blood Pays 100% $0
Part A hospice coinsurance or copayment Pays 100% $0
Part A deductible Not covered $1,736 per benefit period (2026)
Part B deductible Not covered $283 (2026)
Skilled nursing facility coinsurance Not covered Daily coinsurance from day 21
Part B excess charges Not covered Up to 15% above the approved amount
Emergency care outside the U.S. Not covered Full cost

Benefits from Medicare.gov. Massachusetts, Minnesota and Wisconsin standardize plans their own way and do not sell lettered plans.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711  |  Mon–Fri: 5am–7pm, Sat–Sun: 7am–4pm CT

No obligation to enroll

Our Math: What a Plan A Member Still Pays for Common Bills

We ran common situations using 2026 Medicare amounts. The 2027 Part A deductible has not been announced yet, so treat these as a floor.

Situation (2026 amounts) You pay with Plan A You pay with Plan G
One hospital stay, any length $1,736 $0
Two hospital stays in separate benefit periods in one year $3,472 $0
$5,000 of Medicare-approved doctor and outpatient bills $283 $283
$1,000 bill from a doctor who does not accept Medicare assignment Up to $150 extra $0 extra
One hospital stay plus $5,000 of outpatient bills $2,019 $283

Our calculation from CMS 2026 figures: $1,736 Part A deductible, $283 Part B deductible, 15% excess charge limit. Excludes premiums and skilled nursing care.

Easy to miss: The Part A deductible is charged per benefit period, not per year. A benefit period ends after 60 days in a row out of the hospital or a skilled nursing facility, so a later admission can bring a second $1,736 bill.

Why Every Company Must Sell Plan A, and Why That Helps You

Medicare’s official guide states that all companies selling Medicare Supplement policies must offer at least Plan A. Beyond that, each company chooses which letters it sells, so lineups vary.

It is always on the shelf. If a carrier sells Medicare Supplement coverage in your state, Plan A is on its list, even when other letters are not.

It appears in guaranteed-issue rights. In federal guaranteed-issue situations, such as losing employer coverage or a Medicare Advantage plan leaving your area, Plan A is one of the letters a company must sell you without health questions.

It sets the floor. Plan A’s four core benefits are built into almost every other letter.

In most guaranteed-issue situations you can also pick Plan B, D or G, so check for a fuller plan before settling. Our guaranteed issue Medicare Supplement guide lists the situations and deadlines.

Plan A Premiums vs Plan G and Plan N

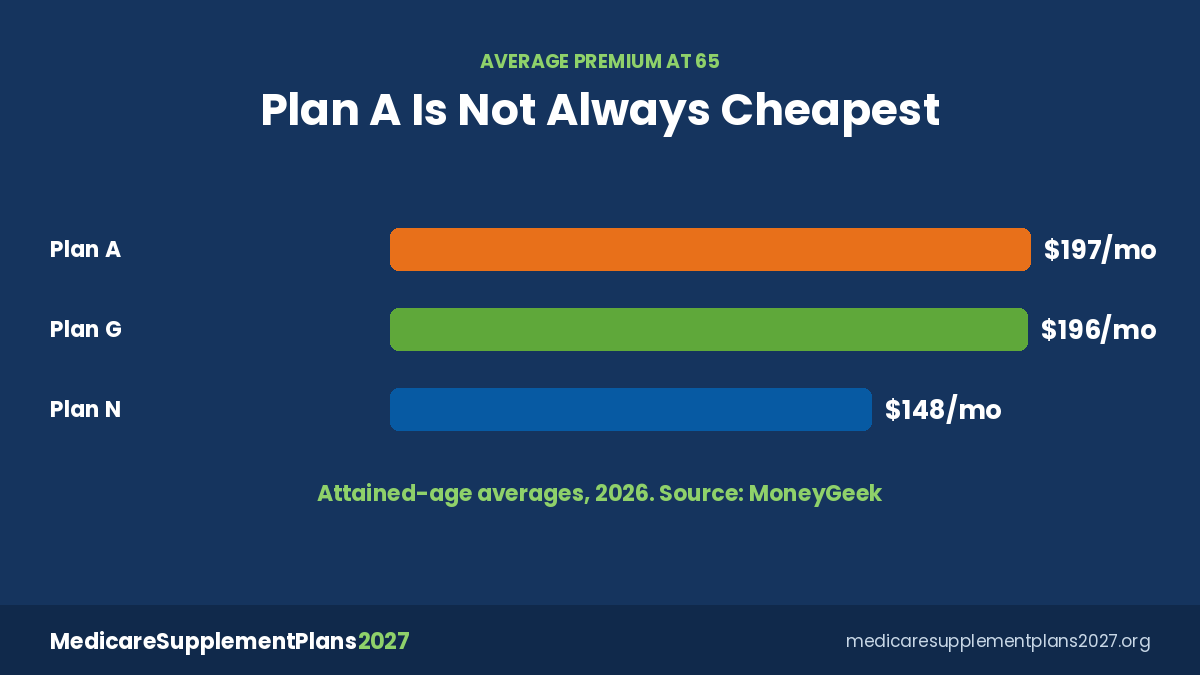
Medicare Supplement Plan A vs Plan G vs Plan N average monthly premiums at age 65, attained-age pricing, 2026

The plan with the fewest benefits is often not the cheapest. Few people buy Plan A, and its premium can land close to Plan G.

Plan (age 65, 2026 averages) Attained-age Issue-age Community-rated
Plan A $197/mo $220/mo $267/mo
Plan G $196/mo $239/mo $306/mo
Plan N $148/mo $188/mo $249/mo

Source: MoneyGeek 2026 Medicare Supplement premium averages for a 65-year-old. Your rate depends on the company, ZIP code, gender, tobacco use and pricing method.

In that data, Plan N beat Plan A under every pricing method, and Plan G matched it on attained-age pricing while also paying the $1,736 hospital deductible. Compare our Medicare Supplement Plan G guide and Plan N guide before you choose.

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

Plan A When You Are Under 65 and on Medicare

This is where Plan A matters most. Federal law generally does not require companies to sell Medicare Supplement plans to people under 65. States fill the gap, and some require only one plan, often Plan A.

Texas. Companies must offer at least Plan A to people under 65 with a disability, in the six months after Part B starts. A 2025 law opens all plans to those with ESRD or ALS. See our Texas Medicare Supplement guide.

Other states. More than 30 states require at least one policy for some people under 65, by counts from Medicare.gov and health-policy trackers.

States with no rule. Under-65 buyers there may find no plan at all until they turn 65.

1

Ask your state insurance department. Find out which letters must be offered to you and how long your window lasts.

2

Take Plan A if it is the only option. Paying the Part A deductible beats paying 20% of every Part B bill with no cap.

3

Mark your 65th birthday. A new six-month Medigap Open Enrollment Period starts at 65, when you can move to any plan with no health questions.

Should You Buy Plan A in 2027? A Quick Decision Check

Buy Plan A if… it is the only plan you can get without medical questions, or a local quote is clearly below Plan G and Plan N and you could cover a $1,736 hospital bill.

Skip Plan A if… you are in your open enrollment at 65. Every plan is open to you, and Plan G or Plan N usually gives more for similar money.

Think twice if… you expect hospital stays, nursing facility rehab or doctors who do not take assignment.

Plan for the upgrade: Moving from Plan A to Plan G later usually means health questions. If you take Plan A under 65, apply for the plan you really want during open enrollment at 65.

People are already searching for Medicare Supplement Plan A 2027 prices, but new rates usually arrive at your policy renewal. For low-cost letters side by side, see the cheapest Medicare Supplement plans.

Bottom Line

Medicare Supplement Plan A pays hospital and doctor coinsurance but leaves you the Part A deductible ($1,736 in 2026), the Part B deductible, skilled nursing coinsurance and excess charges. Every company must sell it, which makes it a strong fallback under 65 or in guaranteed-issue situations. If you can qualify for any plan, price Plan G and Plan N first.

Related: Medicare Supplement Plan B for 2027 Plan A plus the hospital deductible: break-even math and what a rehab stay still costs.

Check 2027 Plan A, G and N prices in your ZIP code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

Medicare Supplement Plan A — Frequently Asked Questions

➤ Is Medicare Supplement Plan A still sold in 2027?

Yes. Plan A is open to new buyers, and every company that sells Medicare Supplement coverage must offer it. Plans C and F are the ones closed to people new to Medicare since 2020.

➤ Does Plan A pay the Medicare hospital deductible?

No. You pay the Part A deductible, $1,736 per benefit period in 2026. CMS has not yet announced the 2027 amount.

➤ Why would anyone pick Plan A over Plan G?

Usually because Plan A is the only plan they can get without health questions, such as under 65 in Texas. In many areas Plan G costs about the same.

➤ Can I get Plan A if I am under 65 and on disability?

It depends on your state. Many states require companies to offer at least one plan to some people under 65, often Plan A.

➤ Does Plan A help with a skilled nursing facility stay?

No. Plan A does not pay the skilled nursing coinsurance that starts on day 21. Plans D, G, M and N cover it in full.

➤ Is Medicare Supplement Plan A the same as Medicare Part A?

No. Part A is Medicare’s hospital insurance. Plan A is a private policy that pays some costs Part A and Part B leave behind.

➤ Will my Plan A premium change in 2027?

It can. Companies file new rates with the state, and changes usually start at your renewal. Attained-age policies also rise as you age.

➤ Can I move from Plan A to Plan G later?

Yes, but outside open enrollment or a guaranteed-issue situation the new company can ask health questions and may decline you. Keep Plan A until the new policy is approved.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711  |  Mon–Fri: 5am–7pm, Sat–Sun: 7am–4pm CT

No obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent