Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Medicare Plan F vs Plan G 2027: Real Rate-Guide Prices and Who Can Still Buy F

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026

Medicare Plan F and Plan G pay the same benefits except one: Plan F covers the Part B deductible ($283 in 2026) and Plan G does not. Only people eligible for Medicare before January 1, 2020 can buy Plan F, and in Nevada’s 2026 state rate guide Plan F cost $284 to $810 more per year than Plan G at five of the six well-known companies we checked.

2027 by the Numbers

$283

2026 Part B deductible, the only benefit gap (CMS)

$292

projected 2027 Part B deductible (Medicare Trustees)

$810

largest yearly Plan F extra cost at age 65 in Nevada’s 2026 guide (our math)

$325 vs $194

average monthly Plan F vs Plan G premium paid by members, 2025 (KFF)

The benefits are almost identical, so the useful questions are different: can you even buy Plan F, and does its extra premium cost more than the one deductible it covers?

To answer the second question with real numbers, we pulled every company that lists both plans in a state insurance department rate guide and did the math. For each plan on its own, see Medicare Supplement Plan F 2027 and Medicare Supplement Plan G 2027.
Compare 2027 Plan F and Plan G Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Plan F and Plan G Are One Deductible Apart

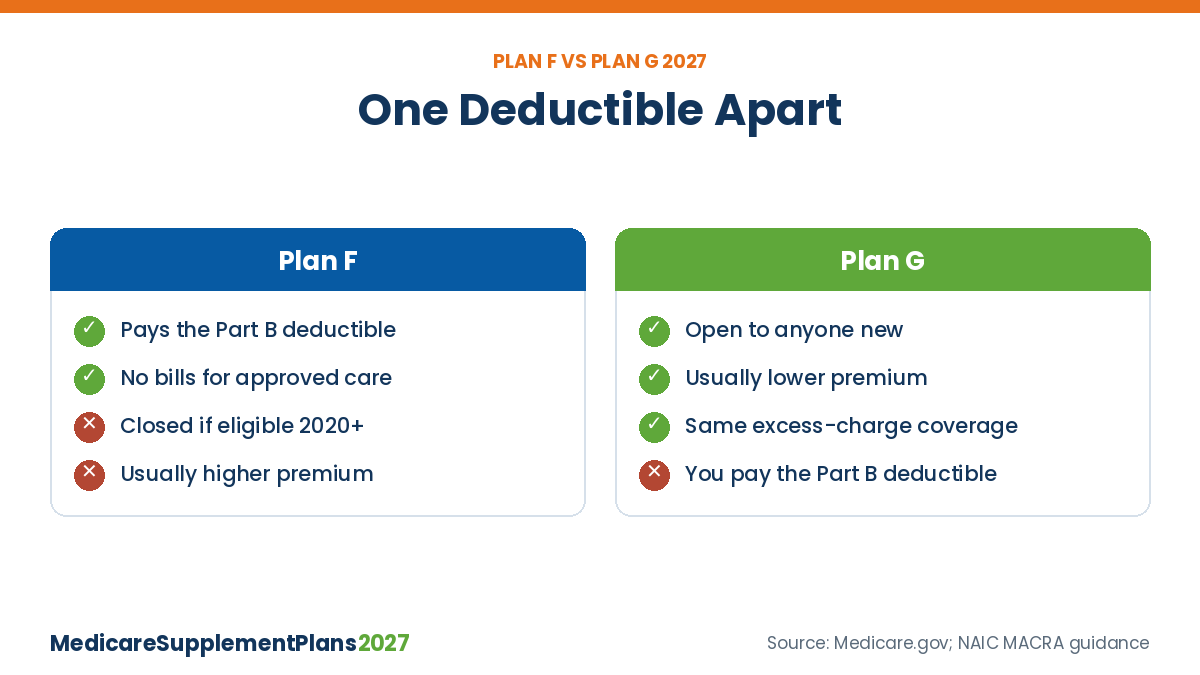
Medicare Plan F vs Plan G 2027: same benefits except the Part B deductible, and Plan F is closed to people new to Medicare since 2020

Both plans pay the Part A deductible ($1,736 in 2026), hospital and doctor coinsurance, Part B excess charges, skilled nursing and hospice coinsurance, the first three pints of blood and 80% of emergency care abroad. Both work with any doctor in the country who takes Medicare. The only line that differs is the yearly Part B deductible.

What you pay yourself With Plan F With Plan G
Part B deductible, 2026 $0 $283
Part B deductible, 2027 (projected) $0 $292
Everything else Medicare approves $0 $0
Monthly premium Usually higher Usually lower

2026 amounts from CMS. The 2027 figure is the Medicare Trustees projection; CMS announces the final amount in November.

Simple test: If Plan F costs more per year than Plan G plus the Part B deductible, Plan G wins on price.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711

No obligation to enroll

Who Counts as Eligible Before 2020 for Plan F

Federal law (MACRA) closed Plan F, High-Deductible Plan F and Plan C to anyone “newly eligible” for Medicare. The NAIC defines that as a person who turns 65 on or after January 1, 2020, or who first becomes eligible for Medicare because of age, disability or end-stage renal disease on or after that date.

Turned 65 before 2020. You can still apply for Plan F in 2027, even if you never bought it before.

On Medicare for a disability before 2020. You were eligible before the cutoff, so Plan F is still open to you where companies sell it.

Eligible before 2020 but delayed enrolling. The NAIC says people who were Medicare-eligible before January 1, 2020 can still be sold Plan C or F.

First eligible in 2020 or later. Plan F is off the table. Plan G is the closest match.

One more rule matters: for newly eligible people, Plans D, G and High-Deductible G stand in for Plans C, F and High-Deductible F wherever the law gives a guaranteed issue right. Learn when those rights apply in our guide to guaranteed issue Medicare Supplement rules.

Real Plan F and Plan G Premiums From a State Rate Guide

The Nevada Division of Insurance publishes a 2026 Medicare Supplement premium comparison guide. It lists yearly premiums for a 65-year-old female non-smoker in Las Vegas (ZIP 89102), based on its September 2024 survey. Fourteen companies list both Plan F and Plan G; the table below shows six of the best-known names.

Company Plan F (yearly) Plan G (yearly) Extra cost of Plan F
Washington National $2,821 $2,011 $810
UnitedHealthcare $2,974 $2,326 $648
State Farm $2,608 $2,072 $536
USAA Life $2,388 $1,888 $500
Cigna $2,200 $1,916 $284
United American $2,623 $2,660 -$37 (F cheaper)

Source: Nevada Division of Insurance, 2026 Medicare Supplement Insurance Premium Comparison Guide (attained-age rates). ‘Extra cost’ column is our calculation. A 65-year-old can buy Plan F only if eligible for Medicare before 2020.

Nevada’s own rates show how much the price of one plan letter swings: among the 14 companies listing both plans, Plan G alone ran from $1,885 to $4,044 a year. See more on Plan G cost in 2027.

Our Break-Even Math: Is Plan F Worth Its Extra Premium?

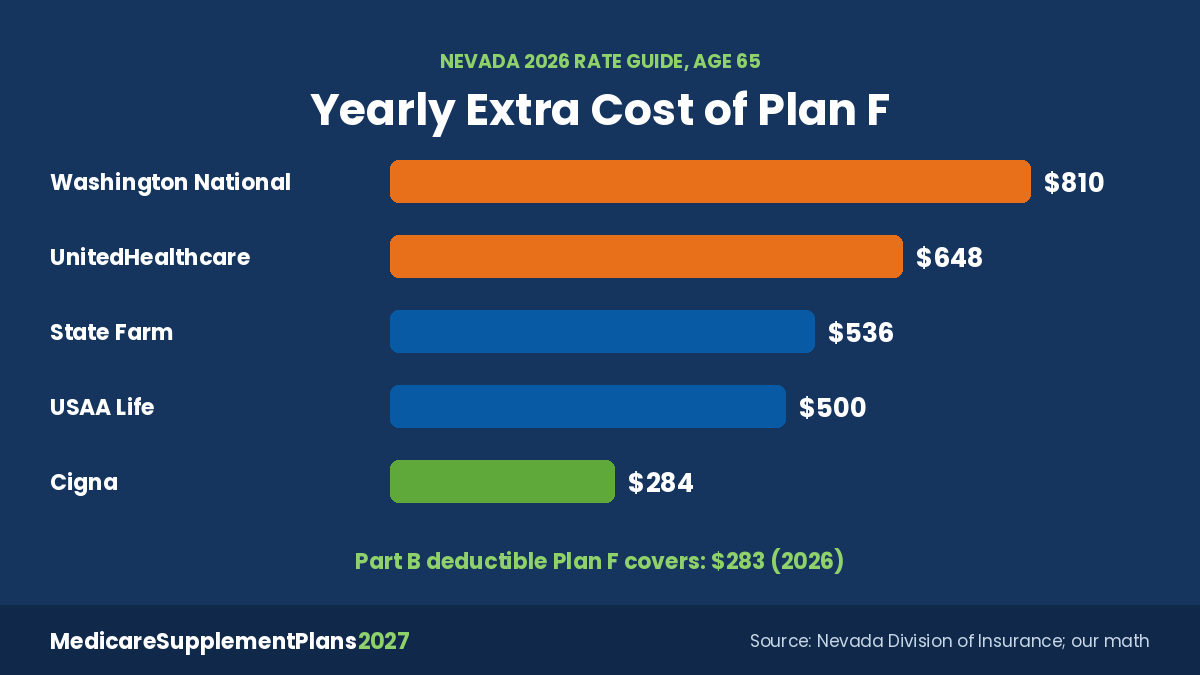
Medicare Plan F vs Plan G extra yearly cost at age 65 by company in Nevada's 2026 rate guide

Plan F only pays you back the Part B deductible, $283 in 2026. So the question for each company is whether the extra premium is bigger than $283. Here is what the six Nevada companies above show.

Four of six companies: Plan G wins. Plan F’s extra cost ran $500 to $810 a year at age 65, far more than the $283 it covers.

Cigna: a tie. Plan F cost $284 more, one dollar more than the deductible. Neither plan saves real money.

United American: the exception. Its Plan F was $37 a year cheaper than its Plan G, so Plan F was the better buy there.

The gap grows with age. At age 70 in the same guide, the Plan F extra cost rose at five of the six companies, for example from $648 to $711 at UnitedHealthcare and from $810 to $818 at Washington National.

Real members feel this too. KFF found that people with Plan F paid an average of $325 a month in 2025, compared with $194 for Plan G. KFF links part of that gap to Plan F’s older, closed group of members, since no one new can join. Plan G pricing also rises over time; read about Plan G rate increases in 2027.

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

High-Deductible Plan F vs High-Deductible Plan G

Both plans also come in a high-deductible version. You pay Medicare-covered costs up to a yearly deductible, then the plan pays like regular F or G. The deductible is $2,950 in 2026 and $3,050 in 2027 for both.

Company (Nevada guide, age 65) High-Deductible F High-Deductible G
United American $569 a year $569 a year
Washington National Not listed $624 a year
Cigna Not listed $744 a year

Source: Nevada Division of Insurance 2026 premium comparison guide.

With a deductible this large, the Part B deductible difference mostly washes out, and High-Deductible F is closed to the same newly eligible group as regular Plan F. Most new buyers who want this design choose High-Deductible Plan G for 2027.

Moving From Plan F to Plan G Without Health Questions

Outside a guaranteed issue situation, a company can usually ask health questions before selling you Plan G. A few states give Plan F owners an easier path. Nevada is one: under NRS 687B.352, starting on the first day of your birthday month and for at least 60 days, your insurer must let you buy any of its Medicare Supplement policies with the same or fewer benefits. Plan G has fewer benefits than Plan F, so it qualifies.

1

Find out if your state has a birthday or anniversary rule. Our page on whether you can change Medicare Supplement plans covers the switching rules.

2

Price Plan G against your current Plan F bill. Use the $283 test: a swap pays off when Plan G plus the deductible costs less than your Plan F premium.

3

Get written approval before you drop Plan F. Keep paying your Plan F premium until the Plan G policy is issued and has a start date.

Bottom Line

Plan F and Plan G differ by one deductible, $283 in 2026. In Nevada’s state rate guide, Plan F’s extra premium beat that deductible at four of six companies, tied at one and lost at one. If you were eligible before 2020, price both plans at the same company before you decide; everyone else should compare Plan G across companies.

Check Plan F and Plan G prices in your ZIP code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Medicare Plan F vs Plan G — Frequently Asked Questions

➤ Is the Part B deductible the only coverage difference between Plan F and Plan G?

Yes. Plan F pays the Part B deductible ($283 in 2026) and Plan G does not. Every other standardized benefit, including excess charges and foreign travel emergency care, is the same.

➤ I got Medicare through a disability in 2018. Can I buy Plan F?

Yes. You became eligible for Medicare before January 1, 2020, so you are not “newly eligible” under the NAIC definition. You can apply for Plan F where companies sell it.

➤ I turned 65 in 2019 but signed up for Part B later. Is Plan F still open to me?

Generally yes. The NAIC says people who were eligible for Medicare before January 1, 2020 can still buy Plan C or Plan F, even if they enroll later.

➤ How much more does Plan F cost than Plan G in a real rate guide?

In Nevada’s 2026 guide, for a 65-year-old woman in Las Vegas, Plan F cost $284 to $810 more per year than Plan G at five companies. At United American, Plan F was $37 a year cheaper.

➤ Why do current Plan F members pay so much more on average?

KFF found Plan F members paid about $325 a month in 2025 versus $194 for Plan G. Plan F covers one extra deductible, and its members are older because no new enrollees can join.

➤ Is High-Deductible Plan F cheaper than High-Deductible Plan G?

They are often priced about the same. In Nevada’s guide, United American charged $569 a year for both at age 65. Both have a $3,050 deductible in 2027.

➤ Does the price gap between Plan F and Plan G grow with age?

Often it does. In the Nevada guide, the extra cost of Plan F at UnitedHealthcare rose from $648 a year at 65 to $711 at 70, and it grew at five of six companies.

➤ Can a birthday rule help me switch from Plan F to Plan G?

In some states, yes. Nevada’s rule lets you buy a policy with the same or fewer benefits from your insurer during at least 60 days starting with your birthday month, without health questions.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711

No obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT