Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

Medicare Supplement Plan J 2027: What It Covered, Keeping It and Switching

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026

Medicare Supplement Plan J has not been sold to new buyers since June 1, 2010, but if you already have it, you can generally keep it and renew it each year. If you want new coverage in 2027, the closest plans you can buy today are Plan G, Plan N and, if you were eligible for Medicare before 2020, Plan F.

2027 by the Numbers

2010

year Plan J closed to new buyers (federal MIPPA law)

$1,600

yearly at-home recovery limit in Plan J (state Plan J outline)

$120

yearly preventive care limit in Plan J (state Plan J outline)

$3,050

2027 High-Deductible Plan G deductible (CMS)

Plan J was once the richest Medicare Supplement plan you could buy. Federal rule changes ended new sales in 2010, but many people still carry a Plan J policy.

This guide explains what Plan J covers, why it closed, the pros and cons of keeping it, and how it compares with the plans sold in 2027. To see every plan letter side by side, use our Medicare Supplement plans comparison chart.
Compare 2027 Medicare Supplement Plan J Alternatives

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

What Medicare Supplement Plan J Covers

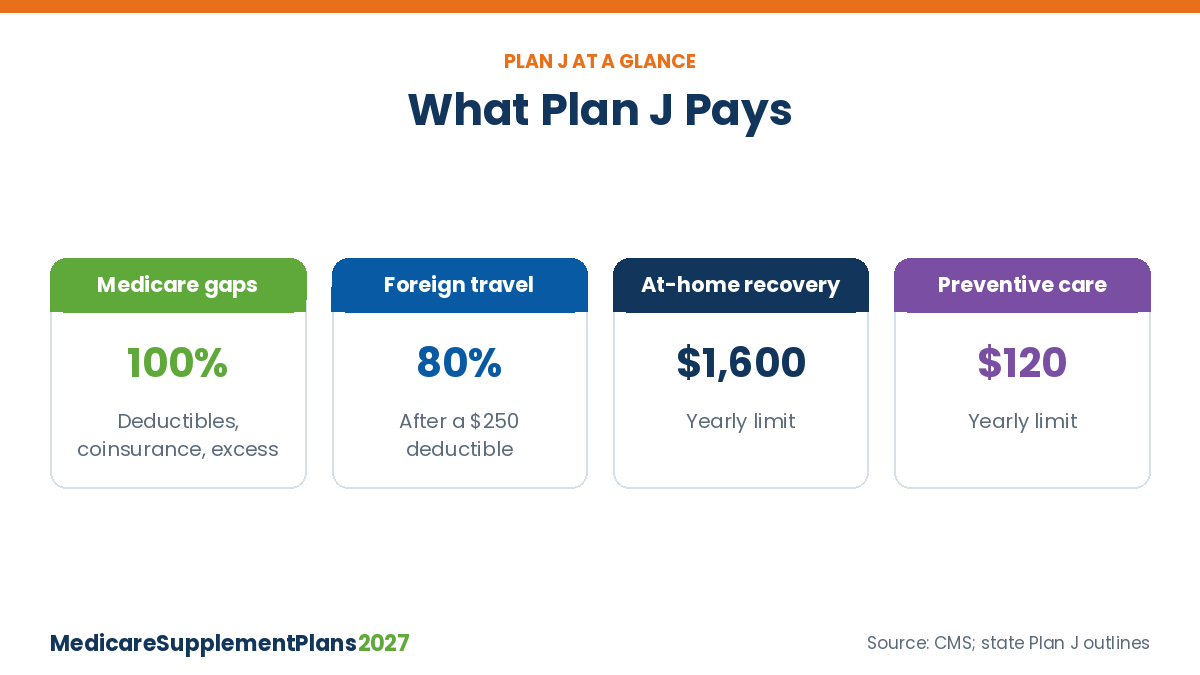
Medicare Supplement Plan J coverage: 100% of Medicare deductibles and coinsurance, 80% foreign travel, $1,600 at-home recovery and $120 preventive care

Plan J was a standardized plan, so its core benefits were the same with every company. It covered the same gaps as Plan F, plus a few extras.

Benefit Plan J pays
Part A hospital coinsurance plus 365 extra days after Medicare benefits end 100%
Part A deductible 100%
Part B deductible 100%
Part B coinsurance or copayment 100%
Part B excess charges 100%
Skilled nursing facility coinsurance 100%
Foreign travel emergency care 80% after a $250 yearly deductible, up to $50,000 lifetime
At-home recovery care Up to $40 per visit, $1,600 per year
Preventive care not covered by Medicare Up to $120 per year

Based on CMS and state insurance department outlines of the pre-2010 Plan J. Your policy’s outline of coverage shows your exact benefits.

Plan J also once included some prescription drug coverage. Medicare Supplement policies with drug coverage could not be sold after December 31, 2005, when Medicare Part D began. People who already had that drug benefit could keep it only if they did not join a Part D plan.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

No obligation to enroll

Why Plan J Stopped Being Sold in 2010

Plan J closed in two steps. First the drug benefit ended for new sales, and then the whole plan letter was retired.

1

January 1, 2006. Under the Medicare Modernization Act, new Medicare Supplement policies could no longer include drug coverage. Drug coverage moved to Part D.

2

June 1, 2010. The Medicare Improvements for Patients and Providers Act of 2008 (MIPPA) took effect. Plans E, H, I and J, including High-Deductible Plan J, were dropped for new buyers.

3

Benefits removed. The at-home recovery and preventive care benefits were removed from all new plans. Medicare now covers many preventive services itself.

4

New plans added. Plans M and N were added, and hospice coverage was added to several plan letters.

Good to know: Plan F and Plan C later closed to people new to Medicare on January 1, 2020. If you were eligible for Medicare before 2020, you may still be able to buy Plan F.

Can You Still Keep Plan J in 2027?

Yes. Medicare.gov states that Plans E, H, I and J are no longer sold, but if you already have one, you can generally keep it. Your benefits stay the same as long as you pay your premium.

It renews every year. Standardized policies bought after 1992 are guaranteed renewable. The company cannot cancel you because of health problems.

Your doctors stay the same. Plan J works with any doctor or hospital in the U.S. that accepts Medicare. There are no networks.

You need separate drug coverage. Most Plan J holders get drug coverage from a Part D plan. Check that you have a Part D plan or other creditable coverage to avoid a late penalty.

Plan J vs Plan G, Plan F and Plan N in 2027

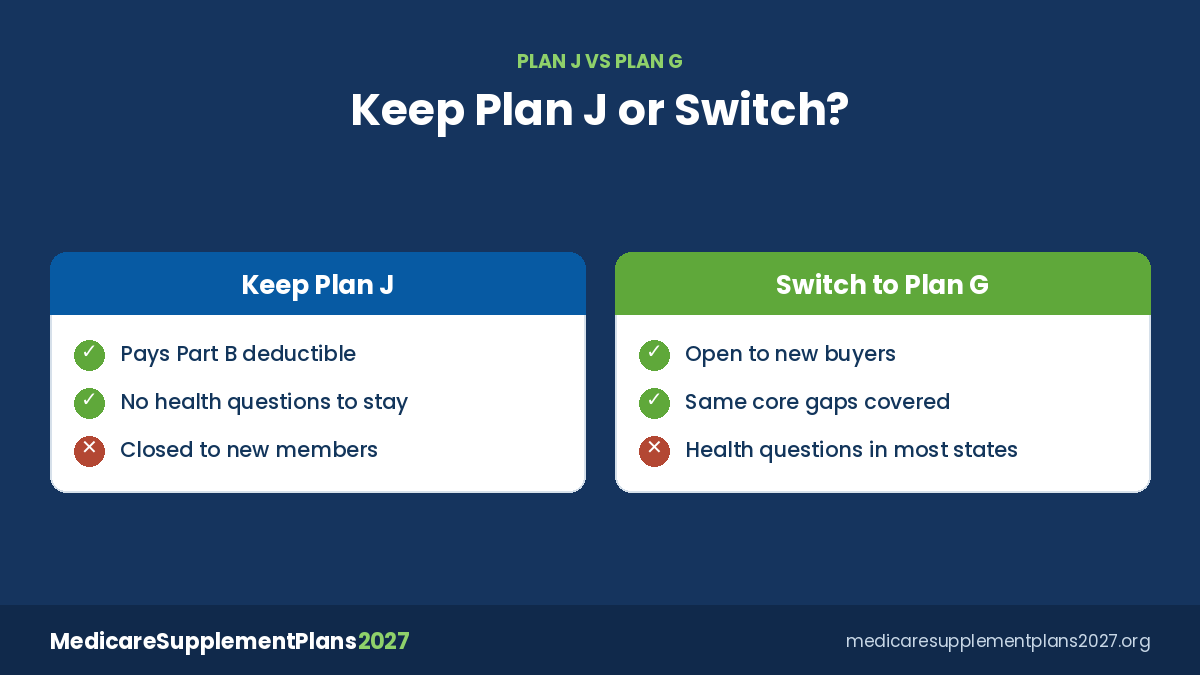
Medicare Supplement Plan J vs Plan G in 2027: keep a closed plan or switch to an open plan

Plan F is the closest match to Plan J. Plan G is the same as Plan F except for the Part B deductible.

Benefit Plan J Plan F Plan G Plan N
Part A deductible Yes Yes Yes Yes
Part B deductible Yes Yes No No
Part B excess charges Yes Yes Yes No
Foreign travel emergency 80% 80% 80% 80%
At-home recovery Yes No No No
Office and ER copays None None None Up to $20 / $50
Sold to new buyers in 2027 No Only if eligible before 2020 Yes Yes

Benefits from Medicare.gov and state Plan J outlines. The Part B deductible is $283 in 2026 and projected at $292 for 2027.

Plan G. The most popular choice for new buyers. You pay only the Part B deductible. See our Medicare Supplement Plan G guide.

Plan F. Pays the Part B deductible too, but only for people eligible for Medicare before 2020. Read our Plan F guide.

Plan N. A lower premium in exchange for copays and no excess charge coverage. Learn more in our Plan N guide.

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Pros and Cons of Keeping Plan J

Plan J still offers very full coverage. The real question is whether its price still makes sense.

Pro: almost nothing out of pocket. Plan J pays the Part A and Part B deductibles, coinsurance and excess charges.

Pro: no health questions to stay. Keeping Plan J means you never have to qualify medically again.

Con: a closed group of members. No new people can join Plan J, so the group only gets older over time. In a closed block like this, premiums can rise faster than in open plans.

Con: the extras are small. The at-home recovery and preventive benefits have low yearly limits, and Medicare already covers many preventive services.

Watch out: Do not cancel Plan J until a new policy is approved and in force. If you drop it first and are turned down for a new plan, you cannot get Plan J back.

How to Switch From Plan J to a 2027 Plan

Most Plan J holders are well past their Medigap Open Enrollment Period. That means in most states a new company can ask health questions and may charge more or turn you down.

1

Check your current rate. Compare your Plan J premium with Plan G, Plan N and, if eligible, Plan F quotes in your ZIP code.

2

Look for state rules. A few states give extra rights to switch plans without health questions. Ask a licensed agent what applies in your state.

3

Apply and get approved. Answer the health questions honestly. Keep paying for Plan J while the new company reviews your application.

4

Use the free look. You have 30 days to decide whether to keep the new policy. Cancel Plan J only after the new plan is active.

Federal guaranteed issue rights apply only in certain situations, such as losing other coverage, and owning Plan J does not create one by itself. Read more about changing Medicare Supplement plans before you apply.

Bottom Line

Medicare Supplement Plan J closed to new buyers on June 1, 2010, but you can generally keep it and renew it each year. Because no one new can join, premiums can rise faster. Compare your Plan J rate with 2027 Plan G, Plan N and Plan F quotes, and only switch after a new policy is approved.

View 2027 plans & rates in your ZIP code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Medicare Supplement Plan J — Frequently Asked Questions

➤ Can I still buy Medicare Supplement Plan J in 2027?

No. Plan J has not been sold to new buyers since June 1, 2010. Plan G, Plan N and, if you were eligible for Medicare before 2020, Plan F are the closest plans you can buy now.

➤ Can I keep my Plan J policy?

Yes. Medicare.gov says that if you already have Plan J, you can generally keep it. It renews each year as long as you pay the premium, even if you have health problems.

➤ What did Plan J cover?

Plan J paid the Part A and Part B deductibles, coinsurance and Part B excess charges, plus 80% of foreign travel emergencies. It also added at-home recovery care up to $1,600 a year and preventive care up to $120 a year.

➤ Does Plan J cover prescription drugs?

Policies sold after 2005 have no drug coverage. Some older Plan J policies had a drug benefit, but it could only be kept by people who did not join Part D. Most people with Plan J get drug coverage from a Part D plan.

➤ What replaced Plan J?

No single plan replaced it. Plan F is the closest match, and Plan G is the same as Plan F except you pay the Part B deductible. Plans M and N were added in 2010.

➤ Why might my Plan J premium keep going up?

No new members can join Plan J, so the insured group gets older over time, and premiums in a closed group like this can rise faster.

➤ Do I need to answer health questions to leave Plan J?

In most states, yes. Outside your Medigap Open Enrollment Period, a new company can review your health. A few states have special rules that make switching easier.

➤ What was High-Deductible Plan J?

It was a version of Plan J that paid only after you met a yearly deductible, which was $1,790 in 2006. It was dropped for new buyers along with regular Plan J in 2010.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

No obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT