Speak with a licensed insurance agent

1-855-409-6195

TTY users 711 Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT
Advertisement

High Deductible Plan F 2027: The $3,050 Deductible, Who Qualifies and Real Cost Scenarios

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 2, 2026

High Deductible Plan F has a $3,050 deductible for 2027, up from $2,950 in 2026, and only people eligible for Medicare before January 1, 2020 can buy it. You pay your share of Medicare-covered costs until that share reaches $3,050 in a calendar year, then the policy pays 100% of covered costs, including Part B excess charges, through December 31.

2027 by the Numbers

$3,050

2027 deductible for High Deductible F and G (CMS)

$2,950

2026 deductible, the year before (CMS)

Jan. 1, 2020

cutoff date: Medicare-eligible before it to buy (MACRA)

$250

separate foreign travel deductible that does not count (plan outlines)

Think of this policy as a catastrophic cap on your Medicare bills. Small bills stay yours; a bad year stops at a fixed number. Because new buyers are shut out, the people searching for it are usually current owners checking the 2027 number, or pre-2020 enrollees weighing a lower premium.

This page stays on the high-deductible version only. For the full-coverage version, read Medicare Supplement Plan F 2027; if you joined Medicare in 2020 or later, the open alternative is High Deductible Plan G for 2027.
Compare 2027 High Deductible Plan F Rates

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

How the 2027 High Deductible Plan F Cap Works

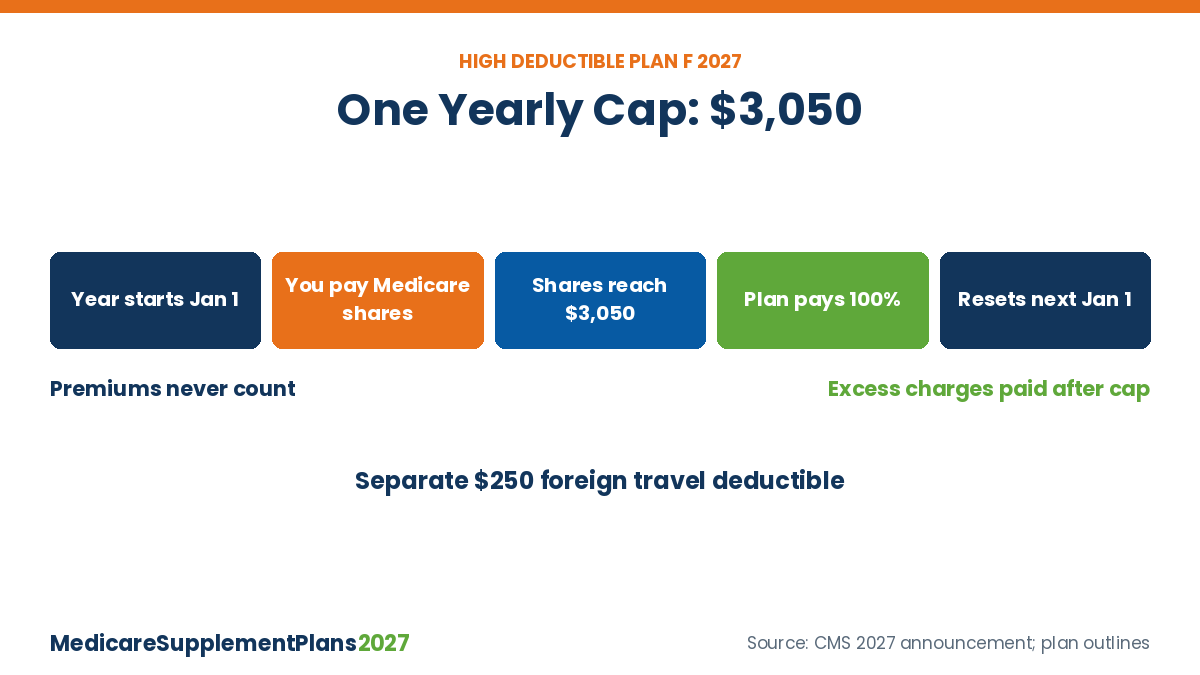
How High Deductible Plan F works in 2027: you pay Medicare cost sharing until $3,050, then the plan pays 100% until the deductible resets January 1

CMS adjusts the figure every fall using the consumer price index, and its October 2026 announcement set the calendar-year 2027 amount at $3,050. The same number applies to the high-deductible versions of Plan F and Plan G, at every company and in every state that sells them.

Stage one: you pay. Each bill Medicare approves leaves you a share, such as a deductible or 20% coinsurance. You pay those shares yourself and they add up toward $3,050.

Stage two: the policy pays. Once your shares for the year hit $3,050, the policy pays the rest of your Medicare cost sharing in full until December 31.

Calendar year, not benefit period. The Part A hospital deductible applies per benefit period, so two separate hospital stays can mean two Part A deductibles. The $3,050 cap counts January to December, which protects you in a year with repeat admissions.

A fresh start each January. On January 1 your running total drops back to zero, even if you met the cap in late December.

Worth knowing: The policy keeps its full Plan F benefit list. It does not drop benefits to lower the price; it only delays when payments start.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711  |  Mon–Fri: 5am–7pm, Sat–Sun: 7am–4pm CT

No obligation to enroll

Who Can Still Buy High Deductible Plan F in 2027

The 2015 Medicare Access and CHIP Reauthorization Act (MACRA) barred the sale of any Medicare Supplement policy that pays the Part B deductible to people who became eligible for Medicare on or after January 1, 2020. The Medicare Rights Center notes that the bar names the high-deductible F option along with Plan F and Plan C.

Your situation Can you apply for High Deductible F?
Turned 65 in 2019 or earlier Yes, where a company sells it
Got Medicare through disability or ESRD before 2020 Yes, eligibility came before the cutoff
Already own High Deductible F Yes, you may keep renewing it
Turned 65 in January 2020 or later No, consider High Deductible G
Lives in Massachusetts, Minnesota or Wisconsin Those states use their own plan designs; the 2020 rule still applies

Sources: MACRA; NAIC guidance; Medicare Rights Center. Owners can renew a policy they hold, though premiums can change each year.

Being eligible is only the first test. Outside your first open enrollment window or a guaranteed issue right, most companies may review your health before accepting you. Our guide to guaranteed issue Medicare Supplement rights explains when they cannot.

What Counts Toward the $3,050, and What Never Does

Plan outlines for this policy use nearly identical wording: the deductible is made of costs the policy would ordinarily pay. Since full Plan F pays almost every Medicare cost-sharing item, almost all of your Medicare cost sharing goes into the total.

Expense Counts toward $3,050?
Part A hospital deductible (each benefit period) Yes
Part B deductible Yes
20% Part B coinsurance for doctors, tests, outpatient care Yes
Skilled nursing daily coinsurance (days 21 to 100) Yes
Part B excess charges up to Medicare’s 15% limit Generally yes, since Plan F pays them; confirm in your outline of coverage
The $250 foreign travel emergency deductible No, it is separate
Monthly premiums No
Drugs, dental, vision, hearing aids, and other care Medicare does not cover No

Based on standard high-deductible Plan F outline-of-coverage wording (2026 plan documents). Wording on excess charges is our reading; each outline of coverage is the final word.

Keep your Medicare Summary Notices. Because you are paying early bills yourself, those notices are the easiest record of how close you are to the cap.

Five 2027 Scenarios: What You Would Actually Pay

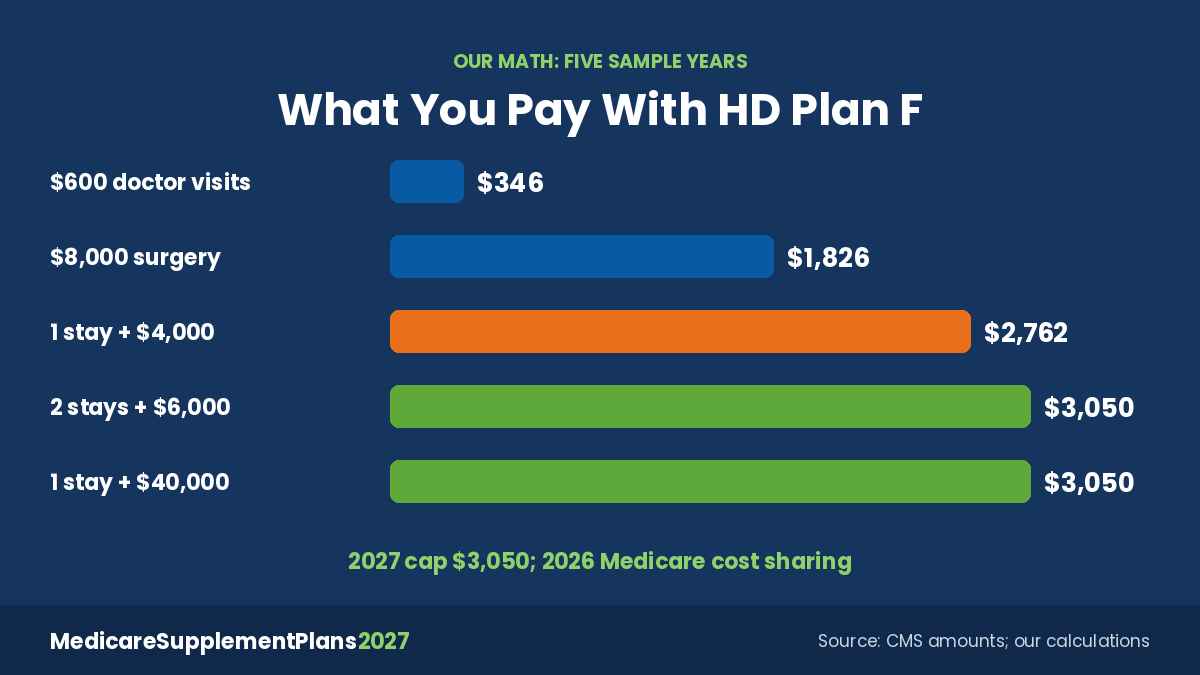
High Deductible Plan F 2027 cost scenarios: what you pay out of pocket in five sample years, capped at $3,050

We ran five sample years through the official rules. Medicare cost sharing uses 2026 amounts ($1,736 Part A deductible, $283 Part B deductible, 20% coinsurance) because CMS had not yet announced 2027 amounts; the cap is the 2027 figure of $3,050.

Sample year Your share under Original Medicare You pay with High Deductible F Policy pays
$600 of doctor visits $346.40 $346.40 $0
$8,000 outpatient surgery $1,826.40 $1,826.40 $0
One hospital stay plus $4,000 of Part B care $2,762.40 $2,762.40 $0
Two hospital stays in separate benefit periods plus $6,000 of Part B care $4,898.40 $3,050 $1,848.40
One hospital stay plus $40,000 of Part B treatment $9,962.40 $3,050 $6,912.40

Our calculations. Premiums are not included. Part B share = $283 deductible plus 20% of the remaining approved amount.

The policy is quiet most years. In the first three sample years, the policy paid nothing; a single hospital stay alone does not reach the cap.

The cap earns its keep in heavy years. Repeat admissions or ongoing treatment are where it pays, up to thousands of dollars.

The worst case is easy to plan for. Your yearly maximum for Medicare-covered care is $3,050 plus premiums. With full Plan F that care cost is $0, so a lower premium has to save you real money to make the trade worth it.

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

High Deductible F Next to High Deductible G: The Excess-Charge Question

Full Plan F and full Plan G differ by one benefit, the Part B deductible. In the high-deductible versions that gap almost disappears, because the Part B deductible is part of what you pay toward the $3,050 anyway.

Feature High Deductible F High Deductible G
2027 deductible $3,050 $3,050
Part B deductible Counts toward the cap Counts toward the cap
Part B excess charges after the cap Paid in full Paid in full
Foreign travel emergencies 80% after a separate $250 deductible 80% after a separate $250 deductible
Who can buy Medicare-eligible before 2020 only Anyone with Parts A and B

Sources: CMS high-deductible announcement; NAIC standardized benefits; plan outlines of coverage.

Excess charges are the part some buyers miss. A doctor who does not accept Medicare assignment can bill up to 15% above the approved amount. Both high-deductible versions cover that extra once the cap is met; Plan C and Plan N never cover it at all. Since out-of-pocket results are so close, many pre-2020 buyers simply compare the two premiums at the same company, as explained in Plan F vs Plan G.

Finding a Policy and Switching In or Out

Fewer companies file this version than full Plan F, and its pool of buyers only shrinks over time. HealthSpring, for example, lists High Deductible Plan F in its 2026 materials, but availability changes by state and year, so a quote search is the only reliable test.

1

Confirm your eligibility date. Your Medicare card or Social Security letter shows when you first qualified. A date before January 1, 2020 keeps this policy open to you.

2

Check whether any company sells it in your ZIP code. If no one does, High Deductible G gives you the same cap and nearly identical results.

3

Set aside the full $3,050. A savings account or emergency fund that can cover the cap removes most of the risk.

4

Know the switching rules before you move. Leaving full Plan F for this version, or moving between high-deductible F and G, usually involves health questions. A few states have birthday rules that may help; see changing Medicare Supplement plans.

5

Do not cancel until approved. Keep paying your current policy until the new one is issued with a start date.

Rule check: Dropping High Deductible F does not end your pre-2020 eligibility, but a company may still turn you down later based on health, so treat any switch as hard to undo.

Bottom Line

High Deductible Plan F trades small, predictable bills for a hard yearly cap of $3,050 in 2027. It is open only to people eligible for Medicare before 2020, and its results are nearly identical to High Deductible G. If you qualify, compare both premiums and keep the full deductible in savings.

See high-deductible plan prices in your ZIP code

Speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent

High Deductible Plan F — Frequently Asked Questions

➤ How much is the High Deductible Plan F deductible in 2027?

It is $3,050 for calendar year 2027, according to the CMS October 2026 announcement. It was $2,950 in 2026, and the new amount starts January 1, 2027.

➤ If I am hospitalized twice in one year, do I pay $3,050 twice?

No. The cap runs by calendar year. You could owe two Part A hospital deductibles under Original Medicare, but your combined share for the year stops at $3,050.

➤ Does the $250 foreign travel deductible count toward the cap?

No. Plan outlines list it as a separate deductible. After you pay it, the policy covers 80% of emergency care abroad up to its lifetime limit.

➤ Do Part B excess charges count toward the $3,050?

Standard wording says costs the policy would ordinarily pay count, and Plan F ordinarily pays excess charges, so they generally count. Check your outline of coverage to confirm.

➤ I joined Medicare in 2021. Is there any way to get High Deductible F?

No. Federal law bars its sale to anyone first eligible on or after January 1, 2020. High Deductible G offers the same $3,050 cap.

➤ Can I keep High Deductible F if I already have it?

Yes. You can keep renewing it as long as you pay the premium. The company can raise rates, but it cannot cancel you for health reasons.

➤ Does High Deductible F help pay for prescriptions?

No. Drug costs are outside it and do not count toward the cap. Prescription coverage comes from a separate Part D plan.

➤ Is High Deductible F sold in Massachusetts, Minnesota or Wisconsin?

Those states standardize Medicare Supplement coverage their own way, so lettered plans are not sold the same way there. The 2020 rule against Part B deductible coverage applies in all three.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Supplement plan up to six months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195.

Medicare Supplement Quotes

Call a Licensed Agent Now

Compare 2027 Plan G, Plan N and more from several insurance companies in one call.

☎ 1-855-409-6195

Advertisement

TTY users 711  |  Mon–Fri: 5am–7pm, Sat–Sun: 7am–4pm CT

No obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-409-6195TTY 711

Mon-Fri: 5am-7pm, Sat-Sun: 7am-4pm CT

Licensed insurance agent