Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 2, 2026
You do not have to buy a Medicare Supplement plan, but if Original Medicare is your only coverage, you probably need one, because Original Medicare has no yearly limit on what you pay out of pocket. People with full Medicaid, TRICARE For Life, or job-based coverage that pays alongside Medicare may not need one.
2027 by the Numbers
None
yearly out-of-pocket limit in Original Medicare (Medicare.gov)
$1,736
2026 Part A hospital deductible, per benefit period (CMS)
$283
2026 Part B deductible (CMS)
$292
projected 2027 Part B deductible (2026 Medicare Trustees Report)
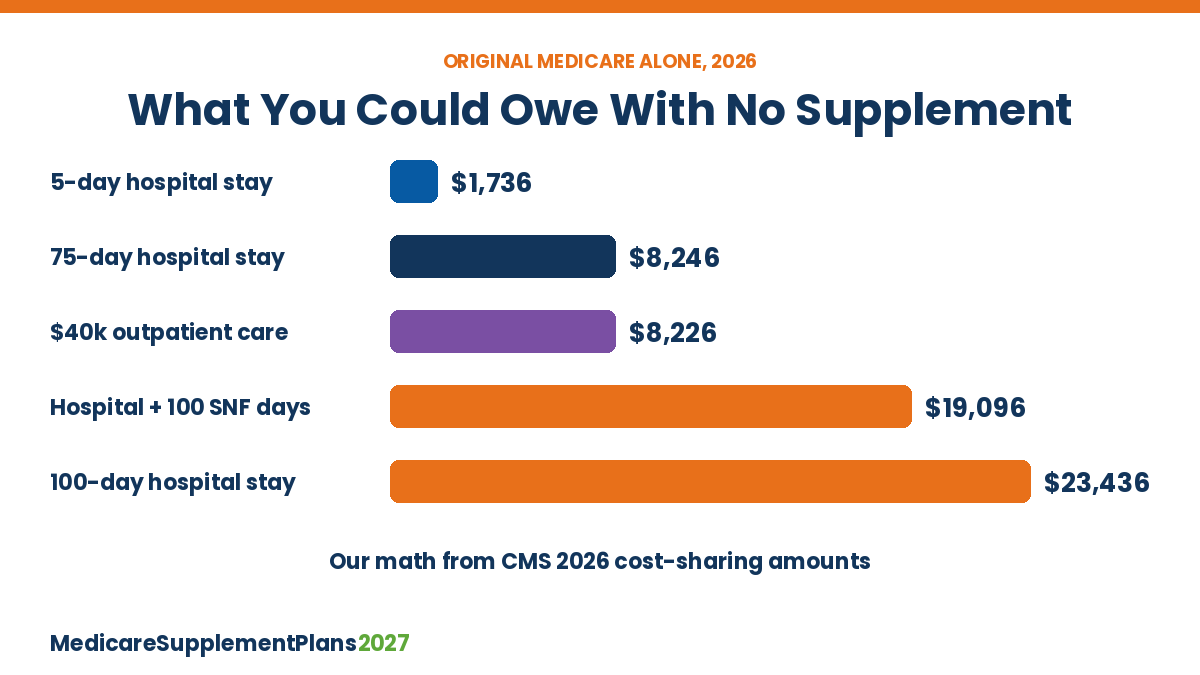
Medicare Part A and Part B pay a large share of hospital and doctor bills, but they leave deductibles, daily hospital charges and a 20% share of most outpatient care to you. There is no ceiling on that share. A Medicare Supplement plan is private insurance that picks up some or all of those leftover costs.
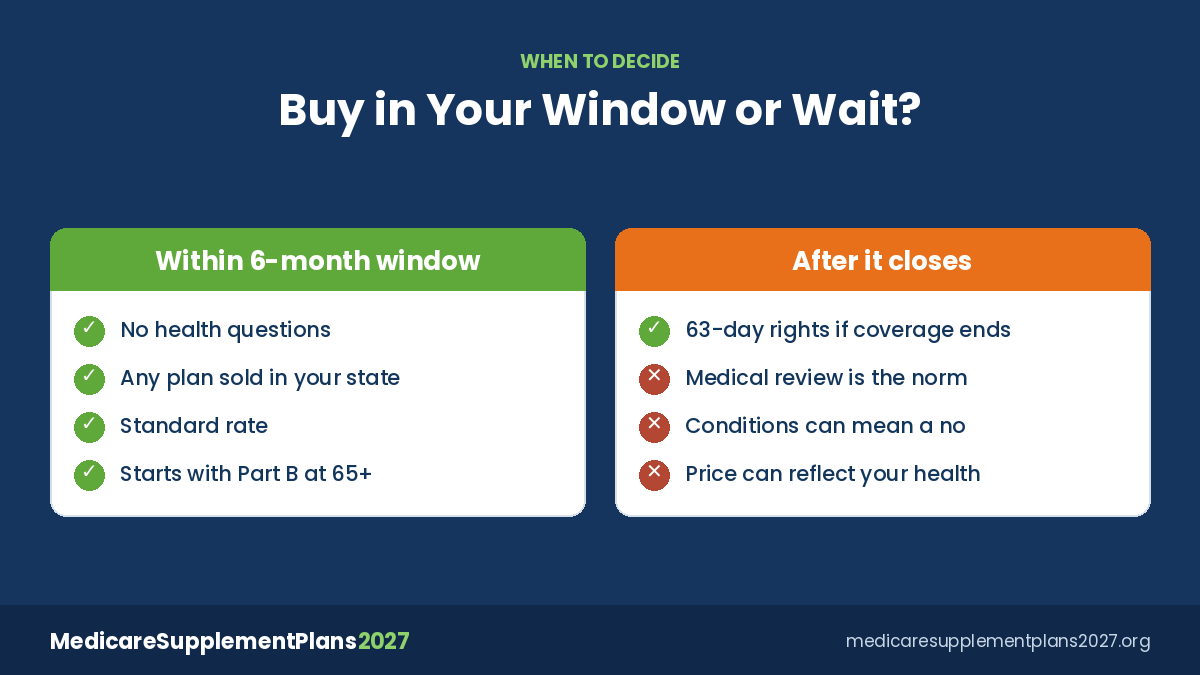
Whether that coverage is worth a monthly premium comes down to one question: does anything else already pay what Medicare leaves behind? Below we work through the dollar exposure using official CMS figures, list the kinds of coverage that can stand in for a supplement, and explain why timing matters as much as the decision itself. If you are weighing a Medicare Advantage plan instead, our Medicare Supplement vs Medicare Advantage comparison covers that choice.